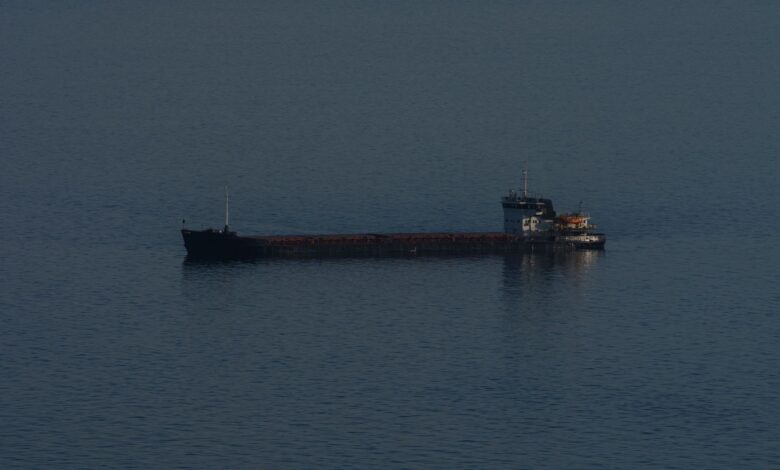
The primary driver behind this volatility is the escalating instability in the Middle East, specifically within the Strait of Hormuz, a critical chokepoint for global oil transport. According to ship-tracking group Kpler, at least 18 vessels have been attacked in the strait over the past two weeks. The risk premium associated with these threats has had a tangible impact on logistics; data indicates that the cost of chartering a large tanker vessel to transport oil through the Strait of Hormuz has quadrupled since September. This increase is largely attributed to higher insurance premiums and the risks faced by maritime crews. These rising transport costs are beginning to offset recent increases in supply, as a growing number of ships continue to move through the strait despite the dangers.
The geopolitical tensions have also prompted broader military and diplomatic responses. Iranian-aligned Houthi rebels claimed attacks on airport, energy, and military targets in Saudi Arabia, as well as a training camp in Yemen. In response, the United Kingdom announced it would begin deploying fighter jets over Saudi Arabia to help protect against further Houthi attacks. Analysts from Deutsche Bank noted that these developments, coupled with the attacks on shipping, have fueled investor speculation that the U.S. administration may be more likely to escalate tensions with Iran after the midterm elections. This perception of prolonged conflict is reflected in the futures market, where advanced oil contracts dated for next year have hit record highs. “The 2027 contracts are moving higher as well as the possible reality of higher for longer oil prices sink in,” said Peter Boockvar, Chief Investment Officer of One Point BFG Wealth Partners, in a note published Tuesday. Deutsche Bank analysts similarly warned that the market is adjusting to a “new normal” in the Middle East, implying an extended period of high oil prices deep into 2027.
These wholesale price increases are poised to ripple through to the U.S. consumer. While U.S. gasoline prices had started the week at a national average of $4.28 per gallon for unleaded—on pace to reach its lowest level in a month—the surge in crude costs is expected to upend this trend. Crude oil typically accounts for more than half the cost per gallon of gasoline; the remainder includes refining, wholesaling, taxes, and local station markups. Historically, while gasoline prices rise quickly when crude prices jump, they often fall more slowly when crude prices drop, a phenomenon often described as “rockets and feathers.” With crude prices now climbing, the downward trend in pump prices is likely to reverse, impacting a significant portion of the electorate. A recent NBC News poll found that 67% of U.S. adults believe gas prices are a “very serious” or “somewhat serious” problem, and a majority reported changing their spending habits due to current economic conditions.
The energy market’s reaction is not isolated to short-term volatility but extends to structural supply and policy considerations. The U.S. Strategic Petroleum Reserve (SPR) remains a key tool for energy security, designed to cushion the blow from supply shocks during crises such as wars or catastrophic storms. However, the SPR is intended for emergency relief to keep vital industries and public transit moving, not to solve long-term structural price issues. Meanwhile, domestic production plays a stabilizing role. U.S. shale oil production helps prevent extreme price spikes by increasing available supply. Recent policy shifts, such as the 2025 decision to reopen more than 1.5 million acres in the Coastal Plain of the Arctic National Wildlife Refuge for oil and gas leasing, reflect an administration focus on expanding domestic supply. This reverses previous policy limitations on Arctic drilling and aims to make the U.S. energy sector more resilient to external shocks.
The interplay between oil and natural gas markets further complicates the picture. A significant rise in oil prices can affect natural gas demand, as some industries may switch to natural gas for certain operations if it becomes relatively more economical, thereby increasing demand for the gas. This cross-commodity dynamic means that the energy transition and market adjustments are not linear. As the U.S. Energy Information Administration (EIA) uses Brent as its primary reference in its Annual Energy Outlook, the global benchmark’s performance is critical for forecasting. Historical context underscores the volatility of these markets: from the 1970s embargo to the 2008 financial crisis crash and the 2020 pandemic-driven plunge below $20 per barrel, oil has always been subject to geopolitical and economic upheaval.
As the midterm elections approach, the focus returns to the consumer impact. The national average gas price, currently at $4.28 per gallon, faces upward pressure from the $112.85 Brent benchmark. While the SPR can provide temporary relief, the fundamental drivers—war risks, insurance costs, and geopolitical escalation—remain unresolved. The market’s adjustment to a “new normal” in the Middle East suggests that the high prices seen in early trading are not merely a temporary blip but a potential baseline for the coming years. For households and businesses, the immediate concern is the end of the recent dip in fuel costs, driven by a supply chain under threat in one of the world’s most vital energy corridors.