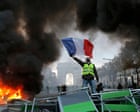
The surge was driven by a combination of political gridlock and social instability. The French government has yet to pass its budget for the coming year, a delay that has eroded market confidence. This fiscal uncertainty coincides with increasingly violent street protests that have shaken the country in recent weeks. The demonstrations, which initially began in September over underfunded schools and the cost of living, have escalated into riots, with reports of looting at high-street retailers and arson attacks on civic buildings, including the town hall in Limoges.
Market participants are increasingly wary of lending to Paris, citing a lack of fiscal discipline. International lenders have accused the government of becoming “fiscally incontinent,” with some, notably Japanese fund managers, withdrawing from the market entirely. Those remaining have demanded higher prices for loans, particularly for longer-term instruments, reflecting the heightened risk premium.
The fiscal strain is evident in official data. France’s budget deficit stood at 5.1% of gross domestic product in 2025, while public debt reached 115.6% of GDP. Forecasts indicate that both the deficit and debt levels are set to increase further in the current financial year without immediate remedial action. The inability to implement spending cuts or revenue increases is largely attributed to parliamentary gridlock following the 2024 snap election, which left no single party with a majority. This impasse has blocked President Emmanuel Macron’s proposed reforms, including raising the pension age from 62 to 64 and reducing state spending.
The domestic turmoil is also impacting the broader eurozone currency. Matthew Ryan, head of market strategy at Ebury, noted that French political risks are dragging down the value of the euro against other major currencies. “The euro continues to lag most major currencies as the political risk premium in France looks unlikely to fade any time soon,” Ryan said. He added that even if a 2027 budget eventually clears parliament, it may be compromised by concessions to both left and right, leaving the underlying deficit problem insufficiently addressed.
Investors are now focused on whether the French legislature can reach a compromise on the pending budget. The outcome will determine the immediate trajectory of French borrowing costs and the extent to which the political risk premium persists in European sovereign debt markets.