The linkage between Treasury yields and mortgage rates is a fundamental mechanism in the U.S. financial architecture. Mortgage-backed securities (MBS), which are partially backed by the full faith and credit of the U.S. government, typically trade at a spread over Treasury yields. When Treasury yields increase due to market expectations of higher interest rates, inflation risks, or supply dynamics, the cost of capital for banks and non-bank lenders rises. Consequently, the headline mortgage rate, often cited as the 30-year fixed-rate mortgage, follows suit. This recent spike to levels unseen since 2023 indicates that the cooling period in borrowing costs may have reached a temporary plateau or reversed, complicating the outlook for the housing market.
For the average American, the implications are direct and significant. Higher mortgage rates reduce purchasing power, meaning that for a given loan amount, the monthly principal and interest payment increases. Alternatively, for a given budget, the maximum loan size a borrower can qualify for decreases. This dynamic typically dampens demand for new home purchases, as affordability metrics tighten. Potential buyers may delay purchases, extending the period of renting, while existing homeowners looking to refinance to lower their debt service costs find fewer opportunities to do so. This can lead to a cooling in housing transaction volumes, as fewer sellers are motivated to list properties if the cost of entering a new home is prohibitive.
The rise in Treasury yields also has wider macroeconomic implications. The 10-year Treasury yield is a key indicator of investor expectations for future economic growth and inflation. An upward trend suggests that markets are pricing in a scenario where the Federal Reserve may maintain higher interest rates for longer to combat persistent inflation, or that investors are demanding a higher risk premium for holding long-term U.S. debt. This environment increases borrowing costs not only for mortgages but also for corporate debt, student loans, and auto loans, potentially stifling broader consumer demand and business investment.
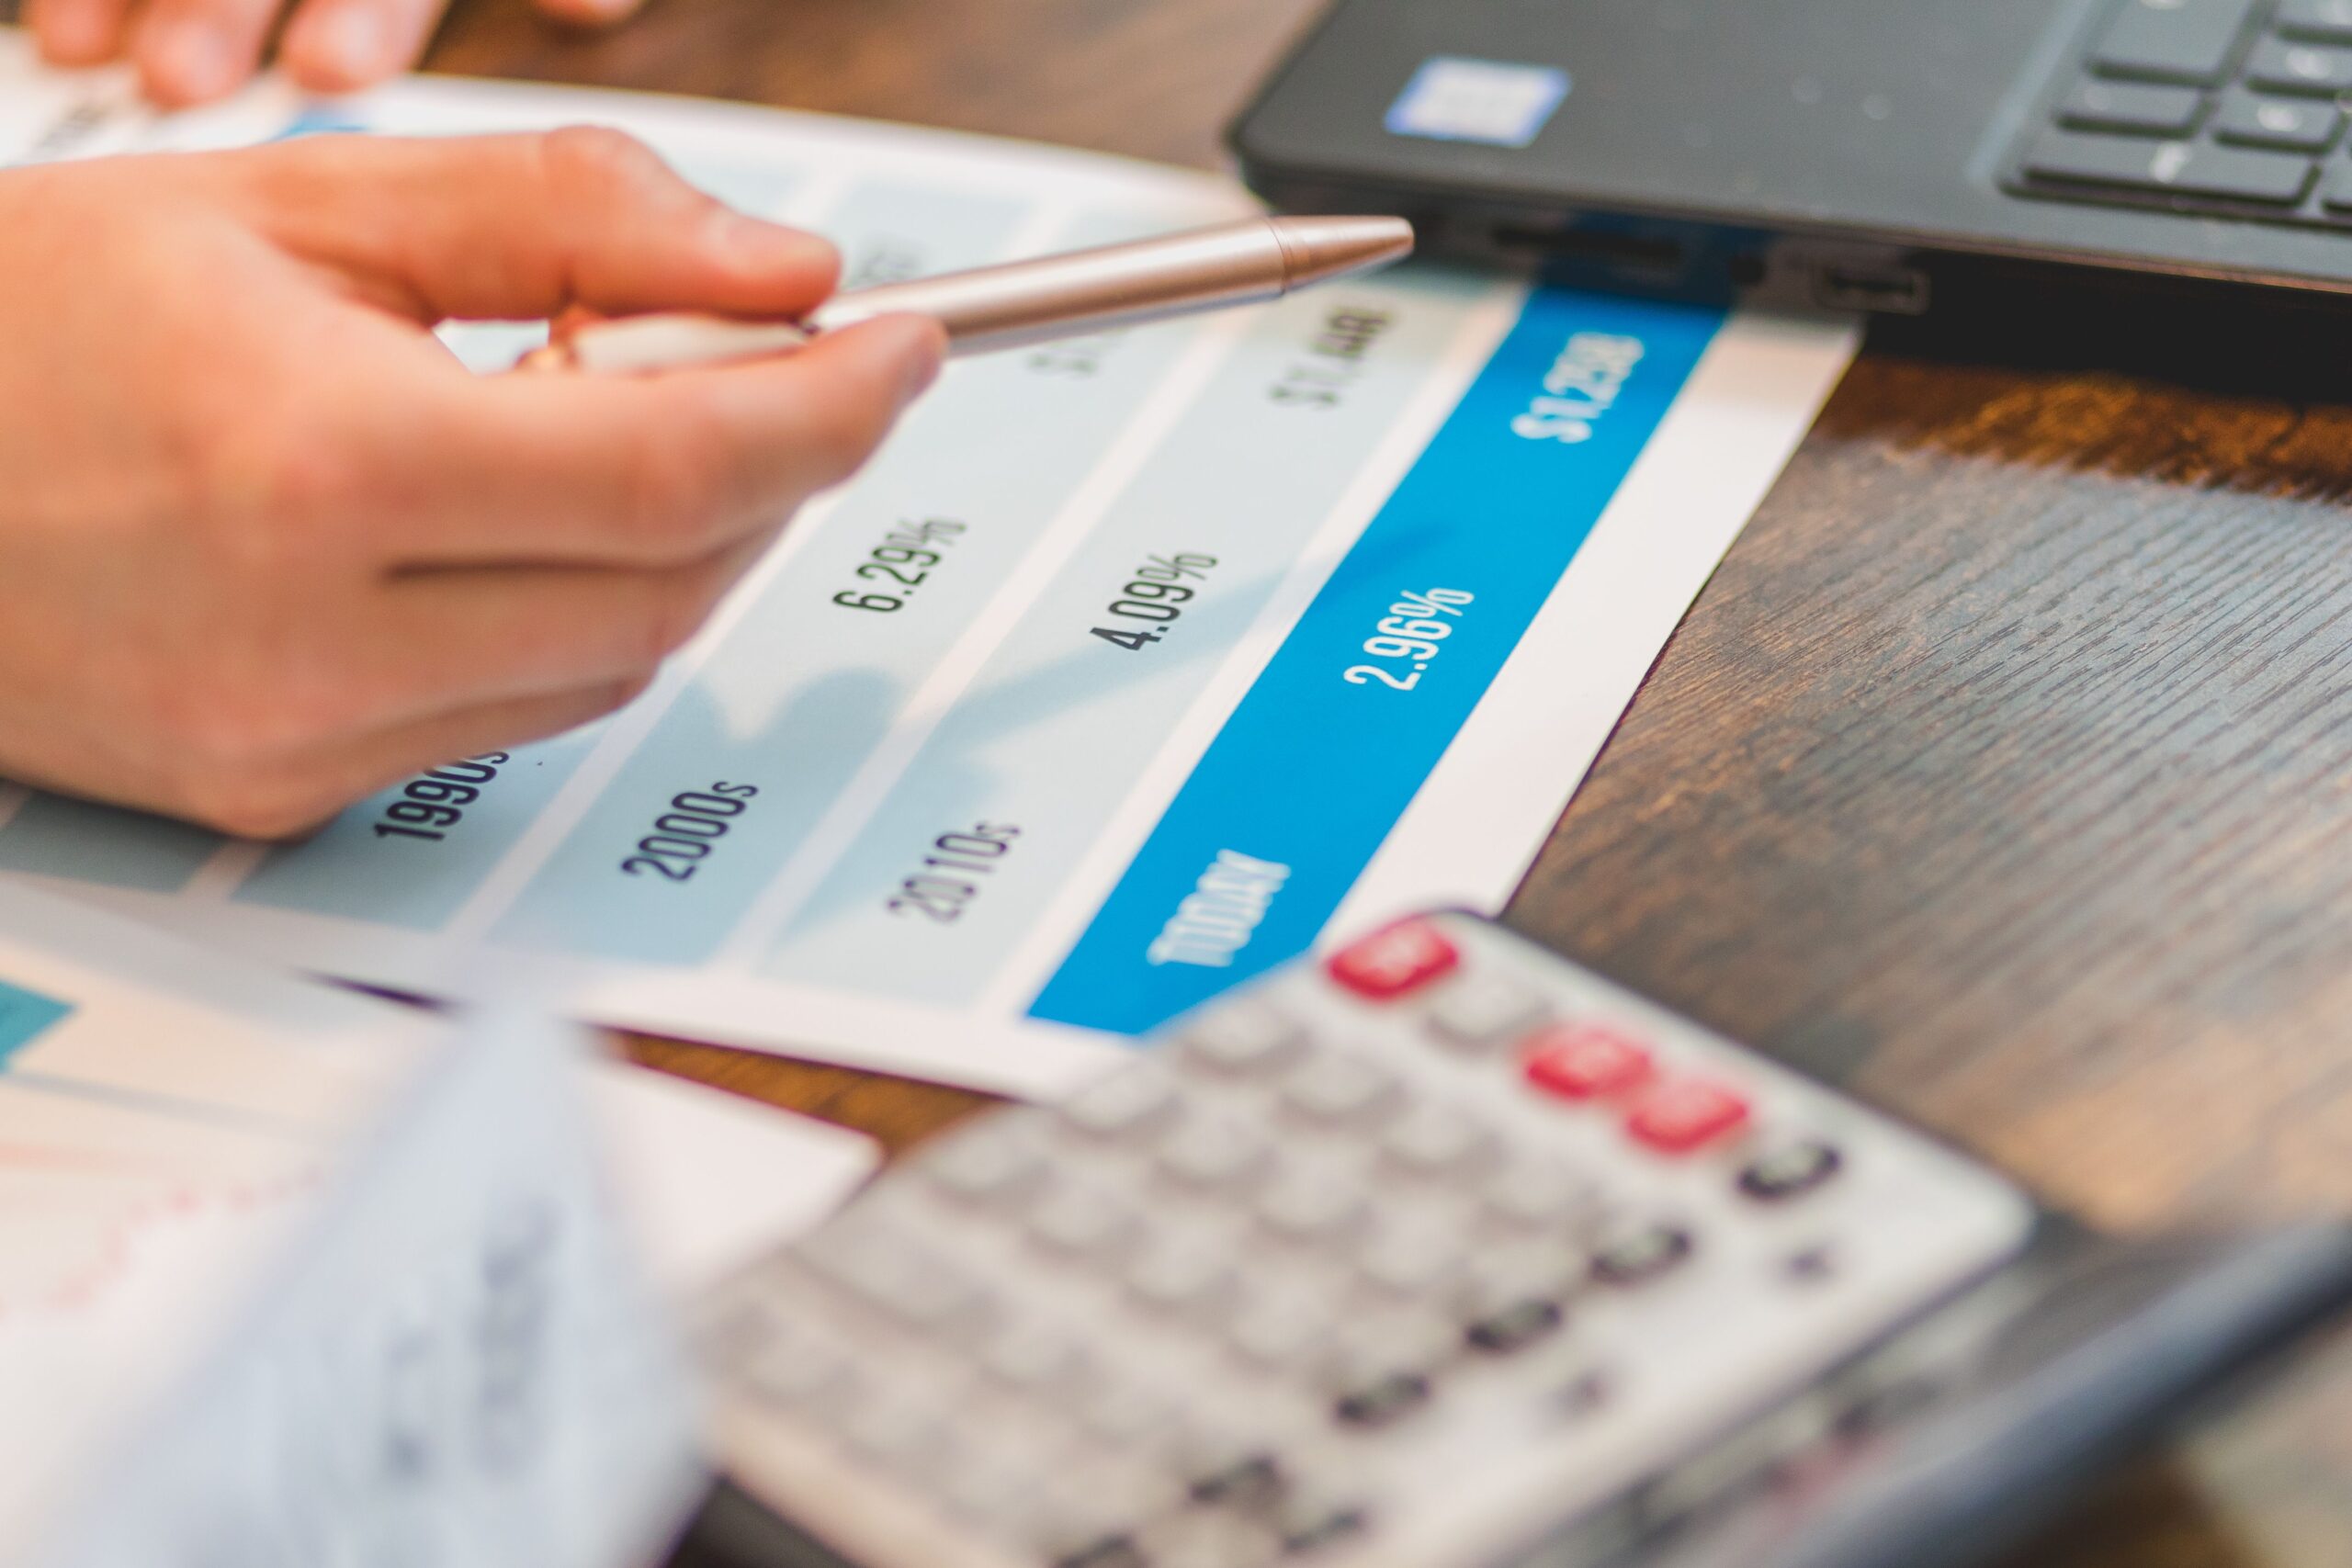
Policy makers, including Treasury Secretary Scott Bessent, who was recently seen at the United Nations headquarters, are closely monitoring these developments. The administration’s fiscal policies and the Federal Reserve’s monetary stance are central to determining the trajectory of yields. If the government increases debt issuance or if inflation proves more stubborn than anticipated, Treasury yields could remain elevated, keeping mortgage rates high. Conversely, if economic data shows a clear deceleration in inflation and growth, the Federal Reserve might signal rate cuts, which would typically lead to lower Treasury yields and, subsequently, lower mortgage rates.
However, the current trend highlights the complexity of the relationship between fiscal policy, monetary policy, and consumer finances. Even if the Federal Reserve were to cut rates, the impact on mortgage rates is not immediate or linear, as it depends on the entire yield curve, not just the federal funds rate. Moreover, supply-side factors in the housing market, such as low inventory of existing homes, can sustain price levels even as affordability worsens. This creates a stalemate where high prices and high rates combine to restrict market mobility.
As the U.S. economy navigates this period of elevated borrowing costs, the focus remains on upcoming economic data releases and Federal Reserve communications. The next few months will be critical in determining whether this rise in mortgage rates is a temporary blip or the beginning of a sustained trend that could reshape the housing market and consumer behavior. For now, the highest levels since 2023 serve as a clear signal that the era of ultra-low borrowing costs is firmly in the past, and consumers and businesses must adjust their financial planning accordingly.