Brent crude futures for November delivery declined by 1.5%, trading at $103.72 per barrel as of 1:10 pm ET. Simultaneously, West Texas Intermediate (WTI) crude for October delivery dropped 2.2% to change hands at $90.62 per barrel. These moves marked a correction from the recent upward trajectory in energy markets, reflecting a shift in investor sentiment toward physical supply fundamentals rather than speculative geopolitical risk.
The primary driver of the price adjustment appears to be the significant increase in regional oil output. Crude exports from the Middle East climbed to 15.5 million barrels per day in September. This figure represents the highest export volume recorded since the current conflict began seven months ago. The recovery is substantial, with September flow rates exceeding 80% of prewar levels. This surge in available supply on global markets has alleviated immediate concerns about tightness, prompting a reduction in the premium typically attached to crude contracts during periods of supply disruption.
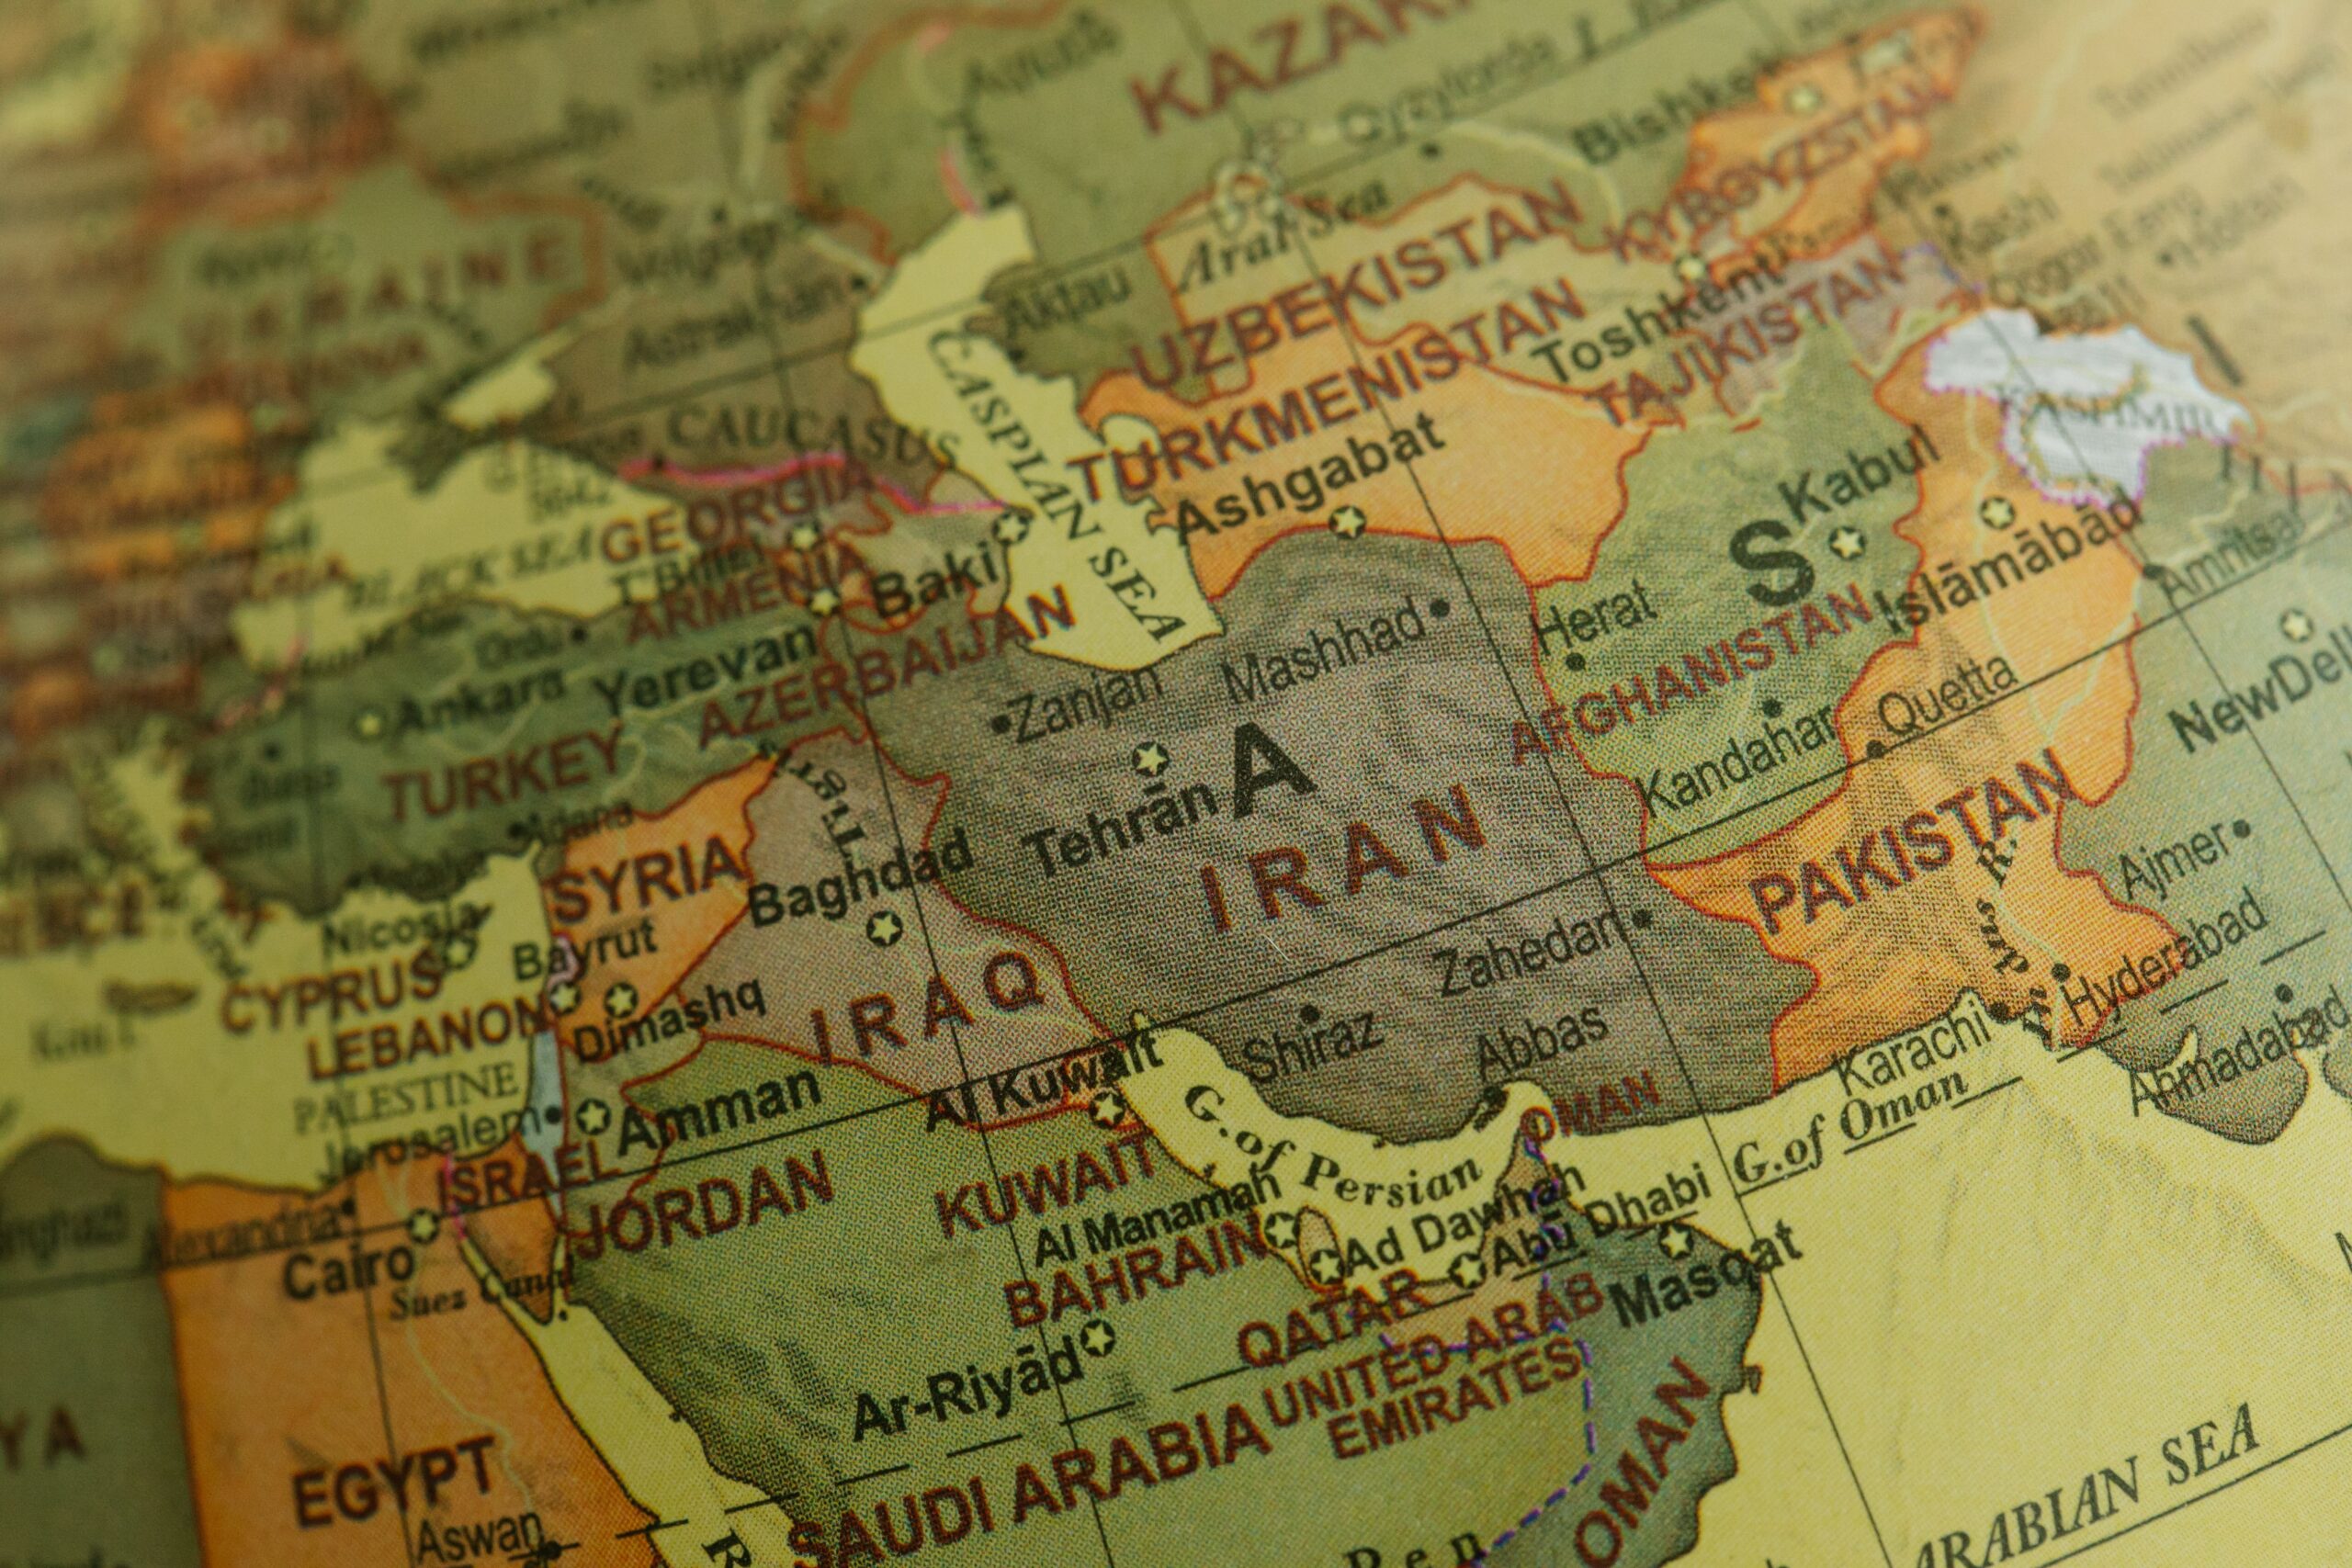
Despite the strong export data, the market remains cautious. The fate of the Iran war remains unresolved, maintaining a layer of volatility in energy trading. Investors are balancing the tangible evidence of increased barrels flowing to global markets against the potential for renewed disruptions should the geopolitical situation deteriorate. The current price action suggests that while the risk premium has not vanished, it is being recalibrated as the physical supply picture improves.
The divergence between Brent and WTI prices, with Brent trading at a significant premium of over $13 per barrel, highlights the specific sensitivity of global benchmark prices to Middle Eastern supply dynamics. The 15.5 million barrels per day export level indicates that major producers in the region have successfully ramped up operations to offset earlier losses, restoring a significant portion of the global supply baseline that had been eroded since the start of the hostilities.
Market participants are now focused on whether this export recovery will sustain its momentum in the coming months. The return to more than 80% of prewar levels suggests that infrastructure and logistics have been restored sufficiently to handle high-volume shipments. However, the final resolution of the conflict will likely dictate the long-term trajectory of oil prices, as any further escalation could reverse the recent gains in export volumes and re-inflate the geopolitical risk premium in crude markets.