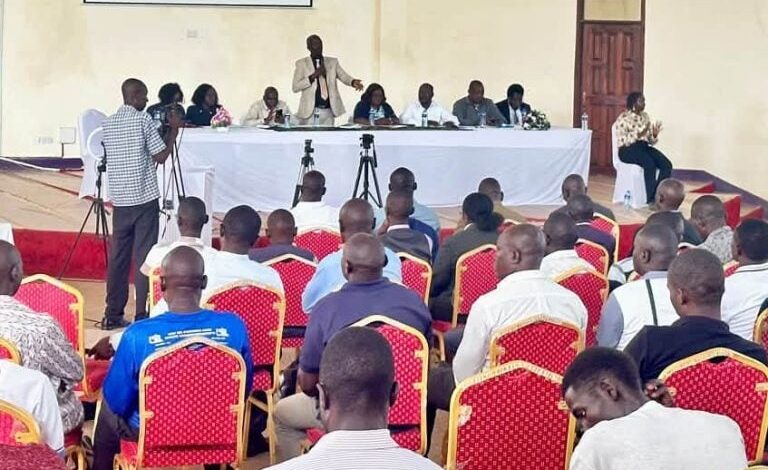
The rejection of this provision was not isolated to Bungoma. During public participation exercises held on September 29, 2026, at both Kibabii University and Alupe University in Busia, stakeholders described the proposed repayment framework as punitive. The National Assembly Departmental Committee on Education, chaired by Tinderet MP Julius Melly, was conducting these consultations as part of a nationwide review of six education-related bills. The central conflict lies in the disconnect between the legislative timeline for debt recovery and the economic reality of Kenya’s youth.
Joseph Ogendo, Deputy Vice-Chancellor for Academics and Students Affairs at Kibabii University, proposed a critical amendment: repayment should only commence within one year of a graduate securing gainful employment. This approach links the financial obligation to actual earning capacity rather than the mere passage of time. Stakeholders argued that the current proposal fails to account for the prolonged period many graduates spend in unemployment or underemployment, effectively penalizing those without immediate income streams.
The financial burden extends beyond the start date. Under the current system, undergraduate and Technical and Vocational Education and Training (TVET) loans attract interest of four percent per annum on the outstanding balance, coupled with a Sh1,000 annual ledger fee. The Muslim Education Council, speaking during a separate session chaired by Mandera South MP Abdul Haro, called for the complete deletion of interest charges (Clause 45(d)) and the rigid repayment timelines (Clause 49(i)). “Let the loanee repay the loan as taken,” the council argued, contending that removing interest would actually accelerate repayment rates by reducing the psychological and financial weight of the debt.
This debate unfolds against a backdrop of rising defaults. As of June 2025, the Higher Education Loans Board (HELB) recorded approximately 256,000 defaulters. In just five months, that number surged by nearly 50 percent to 380,530. The majority of these borrowers come from low-income households, relying on state support to cover tuition, accommodation, and upkeep. The sharp increase in defaults suggests that the existing enforcement mechanisms may be exacerbating financial distress rather than resolving it.
“We tried the differentiated model… it made most of our universities almost close down,” said President William Ruto, acknowledging the failure of previous funding strategies.
In response to years of institutional strain and student complaints, President William Ruto has announced a significant policy pivot. Speaking at State House in Nairobi, the President outlined plans to fully fund university and college education for every qualified student, aiming to begin universal funding in September of this year. Ruto acknowledged that previous models, including the “differentiated” approach that promised 80 percent government funding but often delivered only 40 percent, had left universities on the verge of collapse. The new model seeks to ensure that access to higher education is determined by academic merit rather than a family’s ability to pay.
However, the transition to universal funding is not without its critics. Akello Misori, Secretary-General of the Kenya Union of Post-Primary Education Teachers (Kuppet), raised concerns about the sustainability of the new funding system. He warned that the proposed fund lacks a secure, ring-fenced source of revenue, exposing it to unpredictable annual allocations. “There is no guarantee that continuing students will be funded to completion of their programme,” Misori stated, highlighting the risk that budgetary fluctuations could leave current students stranded midway through their degrees.
The disconnect between the political promise of free education and the legal mechanics of loan recovery creates a complex economic landscape. While the government aims to remove financial barriers to entry, the terms under which existing and future loans are serviced remain a point of contention. Businesses and consumers alike are watching how these policies interact; for instance, employers already face a five percent penalty for failing to remit student loan deductions, a rule that complicates the hiring of fresh graduates.
As the National Assembly moves toward enacting the bill, the focus now shifts to whether the legislature will amend Clause 49 to reflect the realities of the job market. The next critical step is the finalization of the funding model’s revenue sources to ensure that the promise of universal education is not undermined by fiscal instability. For the thousands of graduates currently navigating the default list, the outcome of these parliamentary debates will determine whether their educational investment remains a viable asset or becomes an unmanageable liability.