At the center of the current volatility is the lack of progress in negotiations between Washington and Tehran. For months, the prospect of a diplomatic resolution has offered a potential avenue for easing sanctions or stabilizing regional security, which would support smoother oil flows. However, the recent standstill in these discussions has removed a key stabilizing factor from the market. Traders and analysts are now pricing in a higher risk premium, reflecting the uncertainty surrounding Iran’s ability to influence regional supply or the potential for further disruptions in the Strait of Hormuz, a critical chokepoint for global energy trade. The failure to reach an agreement means that the baseline risk for physical and financial oil markets remains elevated, preventing prices from falling as low as they might have under a scenario of resolved tensions.
Simultaneously, the physical market is characterized by tight fuel inventories. Despite efforts to increase production and move shipments, the drawdown in stocks for refined products and crude has left little buffer against supply shocks. This tightness is particularly evident in key trading hubs where refiners are operating at high utilization rates, competing for limited feedstock. When inventories are thin, any reduction in supply or delay in logistics can trigger disproportionate price responses. The current environment suggests that the market is running on a tightrope, where even minor operational issues or geopolitical headlines can lead to immediate repricing of risk.
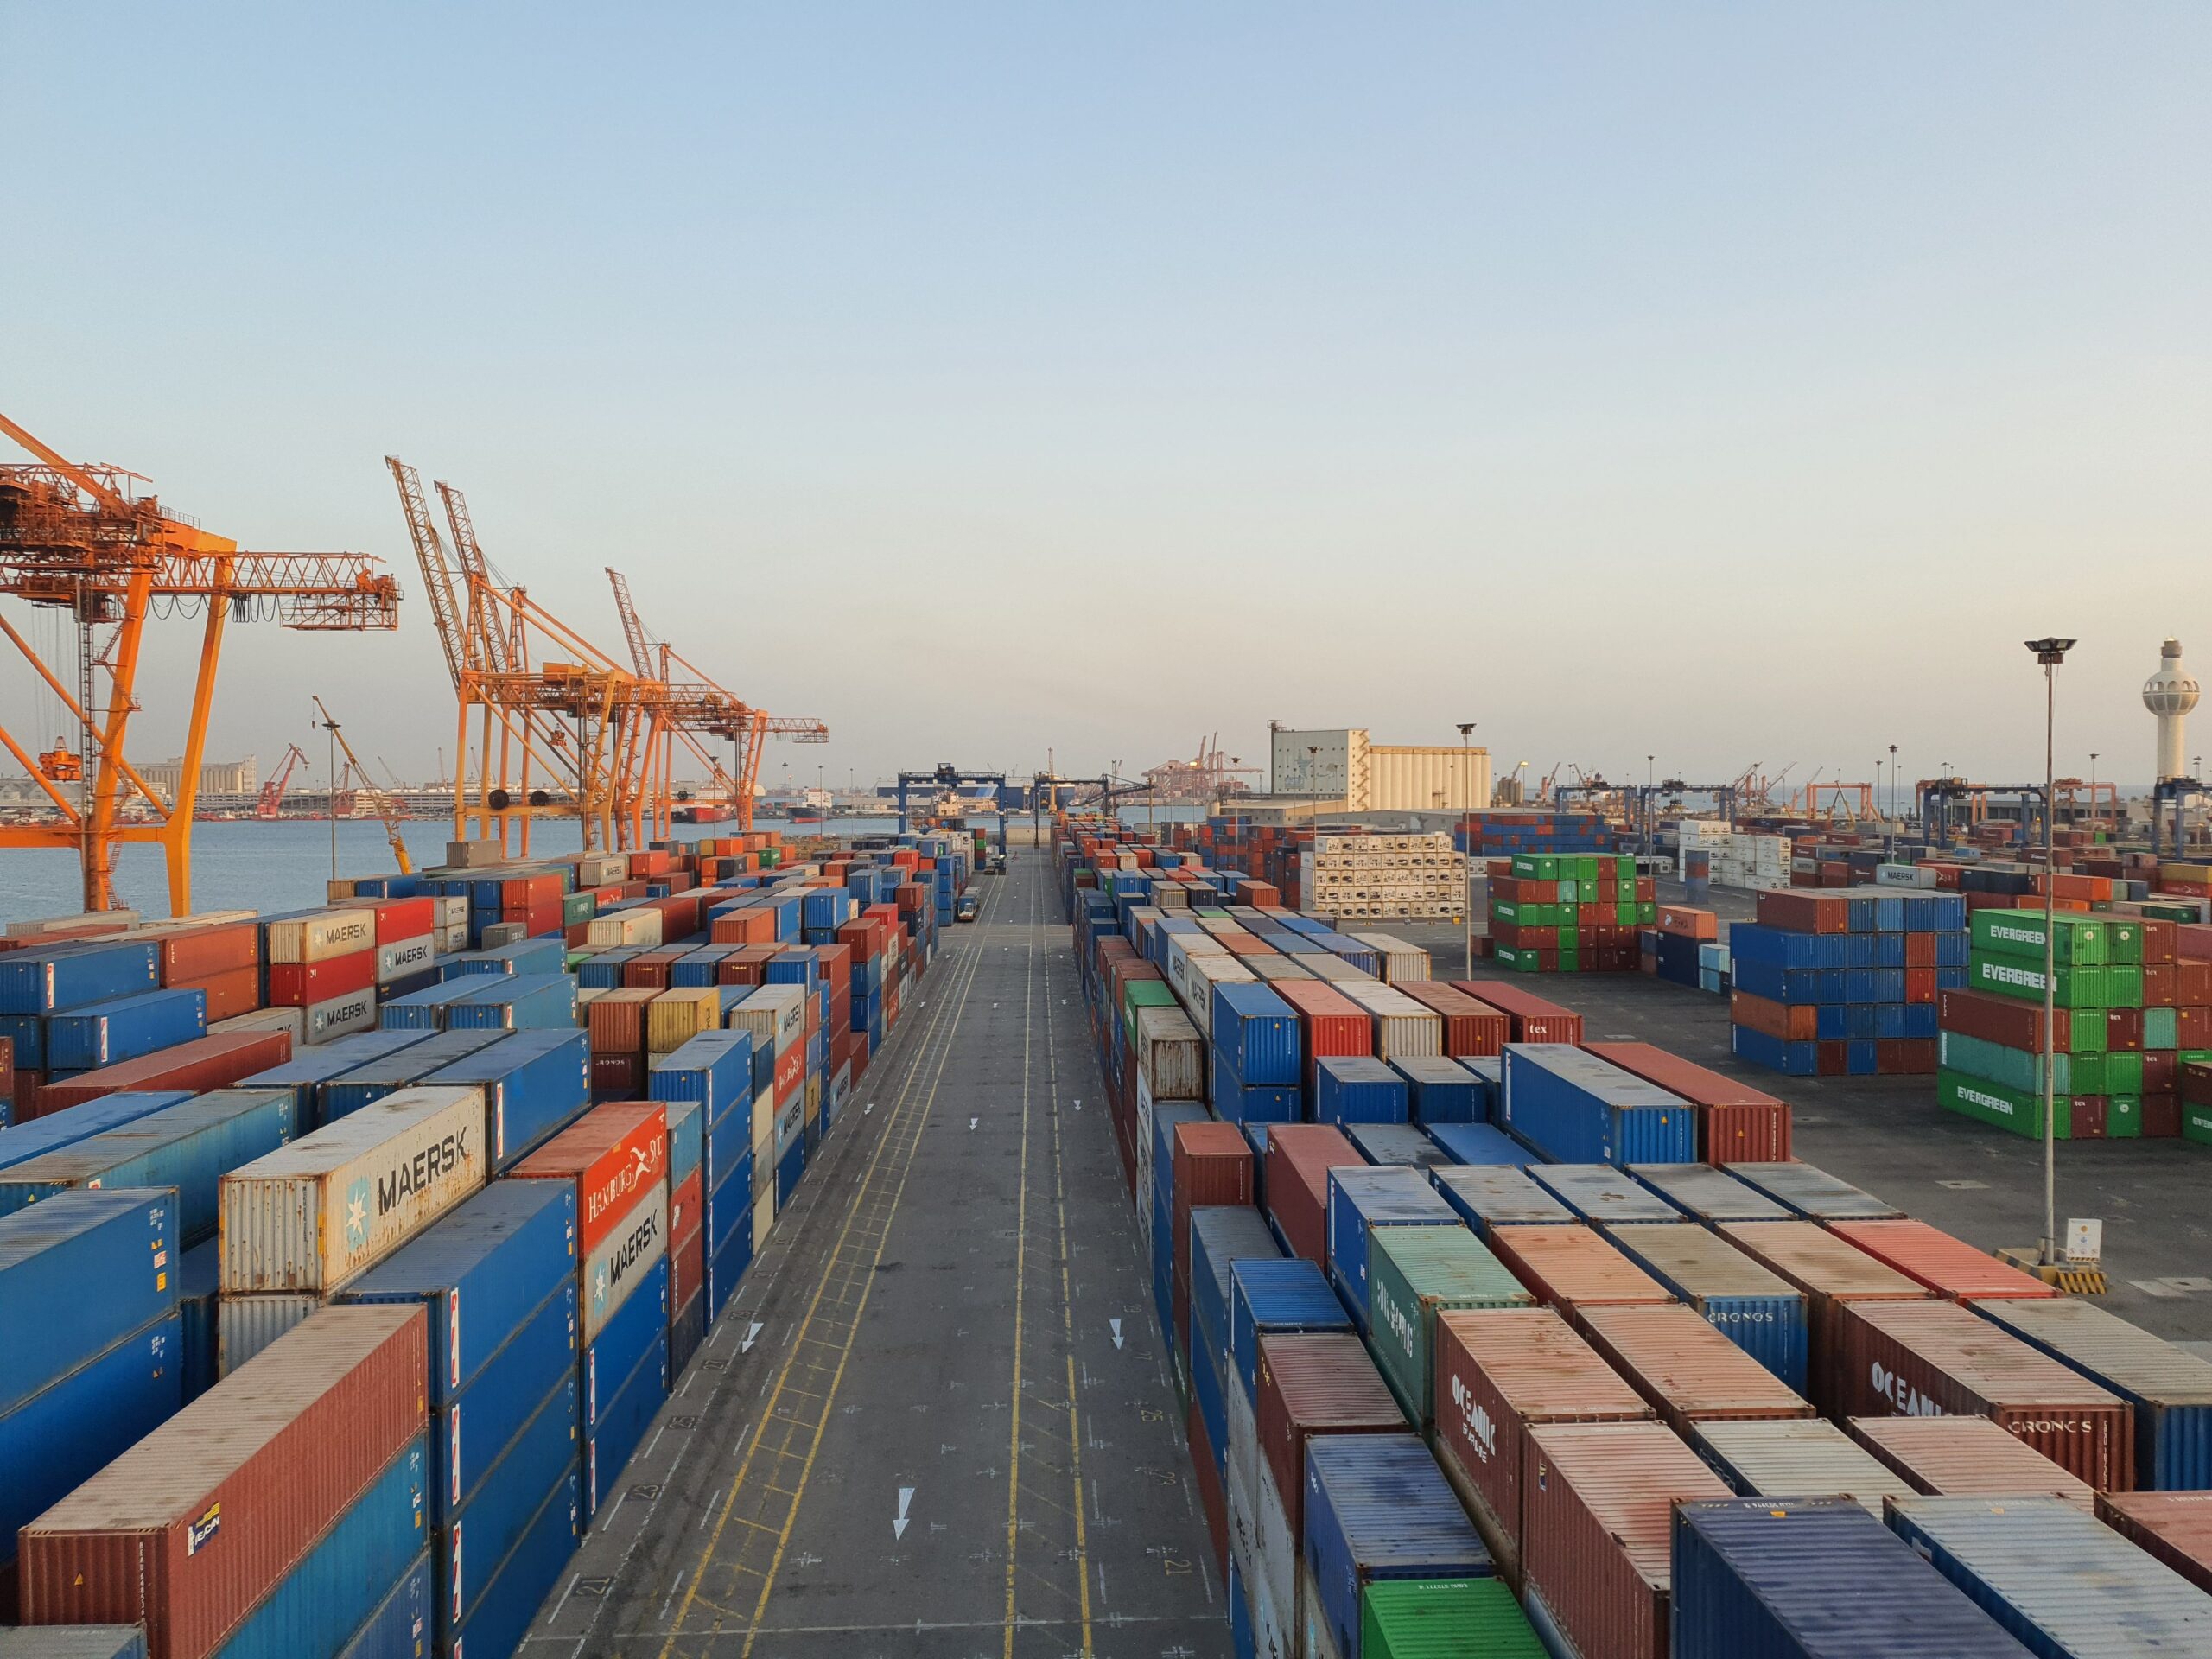
Understanding the mechanics of how oil shipments are moved is crucial to appreciating why these factors are so impactful. The global oil supply chain is a complex network of production, refining, and transportation. When diplomatic channels stall, the uncertainty affects not just the physical barrels in the ground, but the financial instruments and insurance costs associated with moving them. Shipping companies and traders may demand higher premiums for hull insurance or route changes if regional tensions escalate, adding to the landed cost of oil. Furthermore, tight fuel markets mean that alternative sources of supply are limited. If one stream of crude is disrupted or delayed, there is less flexibility to substitute with barrels from another region without incurring significant logistical costs and time delays.
The response from major producers and governments has been cautious. While some OPEC+ members have maintained production levels, the market is watching closely for any signals of supply adjustments. Governments are monitoring the situation to ensure energy security, but without a clear diplomatic breakthrough, policy tools remain largely focused on strategic reserves and regulatory oversight rather than direct market intervention. The uncertainty also affects downstream industries, from petrochemicals to transportation, which must hedge their fuel costs in an environment where price volatility is a constant feature.
Looking ahead, the path for oil prices remains uncertain. A sudden breakthrough in U.S.-Iran talks could lead to a rapid decline in the risk premium, potentially sending prices lower. Conversely, any escalation in regional tensions or a significant drawdown in global inventories could push prices higher. The current $1 per barrel increase is a reflection of these competing forces. It serves as a reminder that the global energy market is not solely driven by fundamental supply and demand balances, but also by the geopolitical and diplomatic landscape. Until there is clarity on the diplomatic front and evidence of a sustained build in global inventories, the oil market is likely to remain volatile, with prices sensitive to both headlines and physical data.
For consumers and industries, the implication is a continued state of flux. While the current price rise is modest, it underscores the fragility of the market in the face of geopolitical and logistical challenges. The resolution of the U.S.-Iran talks and the management of global fuel inventories will be the key determinants of whether oil prices stabilize or continue to trend upward in the coming weeks.