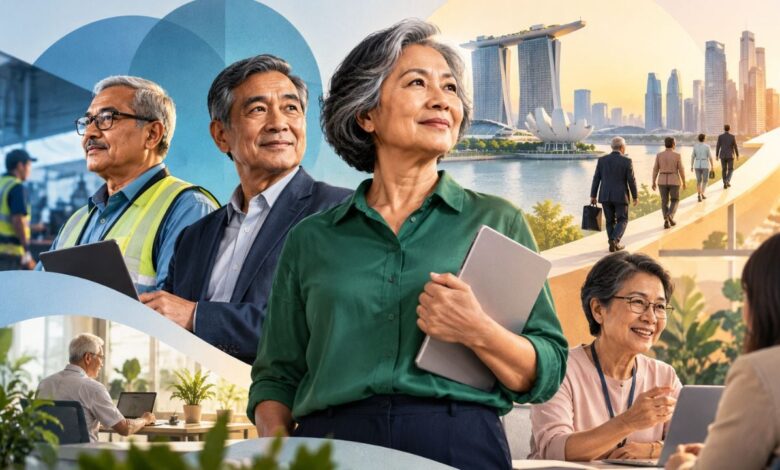
The decision follows the finalization of the Tripartite Workgroup on Senior Employment, a body established in July 2025 to review the nation’s strategy for senior employment. The government accepted all six recommendations put forward by the workgroup, which comprises representatives from the state, employers, and workers. The primary objective of the measures is to provide older employees with greater assurance that they can continue working if they wish to do so, while offering flexible pathways that accommodate changing physical capabilities and personal circumstances.
The shift builds upon recent adjustments. In July, the statutory retirement age was raised to 64, and the re-employment age increased to 69. The next step in this phased approach will see the retirement age rise to 65 and the re-employment age to 70 by 2029. For those nearing the current thresholds, the immediate impact is a reinforcement of employment protection. Eligible workers will have greater legal protection to remain employed until age 64, with the re-employment age extended to 69 in the interim period.
A central component of the new strategy is the introduction of a “flexi-load” programme. This initiative replaces the existing part-time employment grant, which has previously supported approximately 68,500 senior workers and 7,800 employers. The flexi-load programme is intended to allow employers to offer roles with adjustable workloads and corresponding changes in remuneration. A dedicated programme office, led by the Skills and Workforce Development Agency in collaboration with the National Trades Union Congress (NTUC) and the Singapore National Employers Federation (SNEF), will assist employers in developing and implementing these flexible workload arrangements.
Dinesh Vasu Dash, Minister of State for Manpower, emphasized that the goal is to provide meaningful options for seniors who wish to continue working. “For some seniors, this may mean continuing in the same job for longer. For others, it may mean moving into a different role, working at a different pace or adjusting work around changing personal circumstances,” Dash said. The ministry’s 2024 data highlights an existing gap in flexibility: while 85.5% of full-time resident employees aged 50 to 64 were offered flexible working hours and 78.7% had access to flexible work locations, only 74.5% were offered flexible workload arrangements. The new programme aims to close this specific gap.
Beyond workload flexibility, the workgroup recommended “job fractionalisation,” a practice involving breaking conventional jobs into smaller, discrete roles. This approach allows employers to match specific tasks with the skills and availability of senior workers who may no longer find traditional full-time employment suitable. One cited example involves social service organisation Kampong Kapor Community Services, which worked with consulting firm Mercer to develop session-based and case-based roles for experienced workers.
The changes also have significant implications for personal retirement savings, particularly regarding the Supplementary Retirement Scheme (SRS), a voluntary scheme that complements the mandatory Central Provident Fund (CPF). SRS rules link penalty-free withdrawals to the statutory retirement age in effect when an individual makes their first contribution. Consequently, the timing of initial contributions is critical for those who have not yet participated in the scheme.
For individuals making their first SRS contribution before July 1, 2026, the prescribed retirement age for penalty-free withdrawals will be based on the current statutory retirement age of 63. If the first contribution is made on or after July 1, 2026, the prescribed age will be based on the higher statutory age of 64. This distinction affects tax treatment: withdrawals made before the prescribed age are generally fully taxable and subject to a 5% penalty, whereas withdrawals at or after that age are only 50% taxable with no penalty. Financial advisors suggest that individuals consider their overall retirement plan, liquidity needs, and tax situation before rushing to make a contribution solely to lock in the lower age threshold. For those approaching age 65, CPF payout rules remain unchanged, allowing individuals to decide whether to start CPF LIFE payouts at 65 or defer them if they do not require immediate income.
While the higher retirement age provides greater protection and flexibility for those who wish to work longer, it does not mandate employment. The government’s stance is that the changes preserve choice, allowing individuals to retire earlier based on health, caregiving responsibilities, or personal preference. The next formal step in this policy rollout involves the operationalization of the flexi-load programme and the ongoing phase-in of the statutory age increases, with the ultimate targets of 65 and 70 set to take effect in 2029.