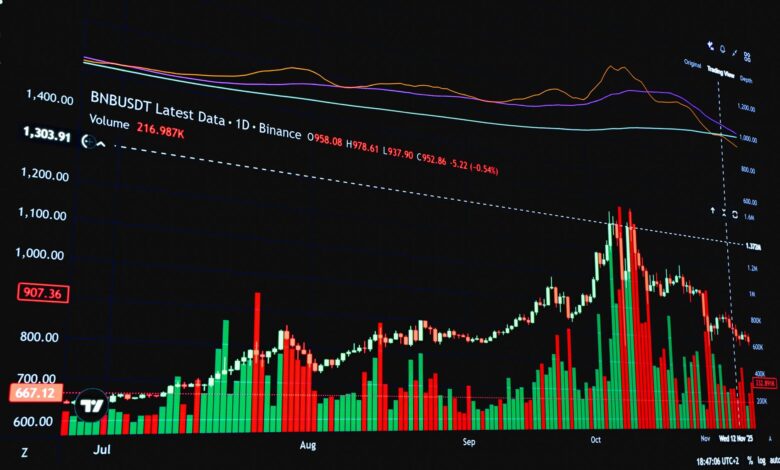
The scale of the exposure is substantial. In 2026 alone, more than $560 billion in debt has been issued worldwide to finance data centers, cloud services, and chip infrastructure. For two years, this leverage has been the primary engine of AI expansion. However, sources indicate that financing conditions have deteriorated sharply in recent weeks. The cost of capital has risen to levels that are prohibitively pricey even for major industry players. This shift is driven not only by rising interest rates but by a fundamental reassessment of risk by major lenders.
Banking institutions are actively re-evaluating their portfolios, moving away from the optimistic valuations that underpinned these loans during the sector’s peak. According to bankers, many AI companies are now rated below-investment grade, or “junk,” which necessitates higher yields to attract investors. Furthermore, banks are reportedly seeking to unload their portfolios of AI data-center loans rather than hold them to maturity. “Every bank is stuffed to the gills with this stuff and looking to dump their portfolios,” one banker noted, highlighting a systemic attempt to reduce exposure to what they view as over-leveraged assets. This behavior suggests a divergence between the valuations assigned to AI infrastructure and the current risk appetite of the financial sector.
This debt dilemma is distinct from the corporate governance crisis currently dominating headlines at Nvidia. The resignation of Jensen Huang, following allegations of an extramarital affair with a woman the government alleges may be a Chinese spy, has triggered a significant sell-off in Nvidia stock. The shares fell 4.34% on Thursday before rebounding nearly 3% in Friday’s premarket trading, though they remain down 27.28% over the past month. While this leadership vacuum raises questions about succession and board oversight, analysts argue that the underlying debt issue is more existential and cannot be resolved through better corporate governance alone.
The market reaction to Nvidia’s turmoil has been mixed, reflecting a broader hesitation regarding the sector’s sustainability. Prime Capital Financial CIO Will McGough noted that Nvidia’s order visibility over the next 12 to 24 months supports revenue and earnings, with the stock trading at roughly 10 times forward earnings. However, he warned that rebuilding investor confidence will take time. Other experts, such as Seaport Research’s Jay Goldberg, maintain a bearish outlook, arguing that customers may accelerate shifts toward competitors like AMD and custom chips, particularly given Nvidia’s limited available chip capacity. Columbia Law School professor Dorothy Lund pointed to governance weaknesses, including the lack of a clear succession plan and a flat management structure where more than 60 executives reportedly report directly to Huang, as factors eroding institutional trust.
The economic implications of the debt crunch extend beyond individual companies. As financing becomes more expensive and harder to secure, the ability of AI firms to expand their infrastructure may be constrained. This could moderate the pace of technological deployment, affecting sectors ranging from medicine to national security that rely on AI advancements. The situation is compounded by political dynamics, with reports suggesting that policy environments in Washington may become less favorable to aggressive tech expansion in the coming term.
Investors are now forced to distinguish between short-term volatility driven by corporate scandals and longer-term structural constraints imposed by the credit cycle. The $560 billion debt load represents a significant bet on future cash flows that may not materialize at the pace previously assumed. As banks tighten their lending standards, the AI industry may face a period of slower growth or consolidation, where only the most financially robust players can sustain their expansion. The convergence of leadership instability at key firms like Nvidia and a hostile credit environment creates a complex risk landscape that will likely define the sector’s trajectory for the remainder of the year.