At the center of this expansion is Southern Copper, which has prioritized a US$15 billion pipeline of projects in Peru. This massive capital commitment underscores the company’s long-term confidence in the country’s resource base, despite recent setbacks. In the short term, however, the sector has experienced tangible supply disruptions. Recent reports indicate that a mine halt in Peru, compounded by severe storms in Chile, has added to existing copper supply struggles. These events highlight the vulnerability of the regional supply chain, where extreme weather events and operational stoppages can quickly tighten global markets.
The economic significance of these developments is best understood through the lens of 2027 projections. Industry observers, including entrepreneur Víctor Gobitz, anticipate a positive year for Peruvian mining despite the lingering effects of El Niño. Gobitz notes that the fundamental trend in copper prices remains unchanged, suggesting that demand dynamics will continue to support the sector. The Tía María project is viewed as the “star” of this 2027 outlook, a designation that reflects both its potential volume contribution and the intense scrutiny it faces.
However, the path to realizing this US$8 billion in new capacity is not without significant obstacles. A primary concern is the bureaucratic environment. While Peru’s resource wealth is substantial, the mining sector faces major bureaucratic hurdles that can delay project timelines and increase costs. These regulatory challenges create uncertainty for investors who must weigh the long-term value of the country’s 12% share of global reserves against the short-term friction of permitting and operational compliance.
The interplay between policy and market forces is further complicated by the broader global energy transition. The world is projected to add approximately 4,770 gigawatts of renewable electric generating capacity between 2026 and 2031, a 57% increase over the 2020–2025 period. This surge in renewable infrastructure is a critical driver of copper demand, as the technology relies heavily on the metal for transmission and distribution. For Peru, this global shift presents a structural tailwind, ensuring that even if domestic regulatory processes are slow, the international appetite for its copper remains robust.
Businesses in the region are responding by focusing on large-scale, high-value projects to justify the entry costs associated with Peru’s regulatory landscape. Southern Copper’s US$15 billion pipeline is a clear example of this strategy, favoring integrated operations that can withstand market volatility. Meanwhile, smaller players and contractors are navigating a more cautious environment, with global capital spending in related sectors, such as food and beverage packaging, showing a more hesitant posture due to geopolitical tensions and tariff pressures. While these macroeconomic headwinds affect various industries, the mining sector in Peru appears insulated by the critical nature of its commodities.
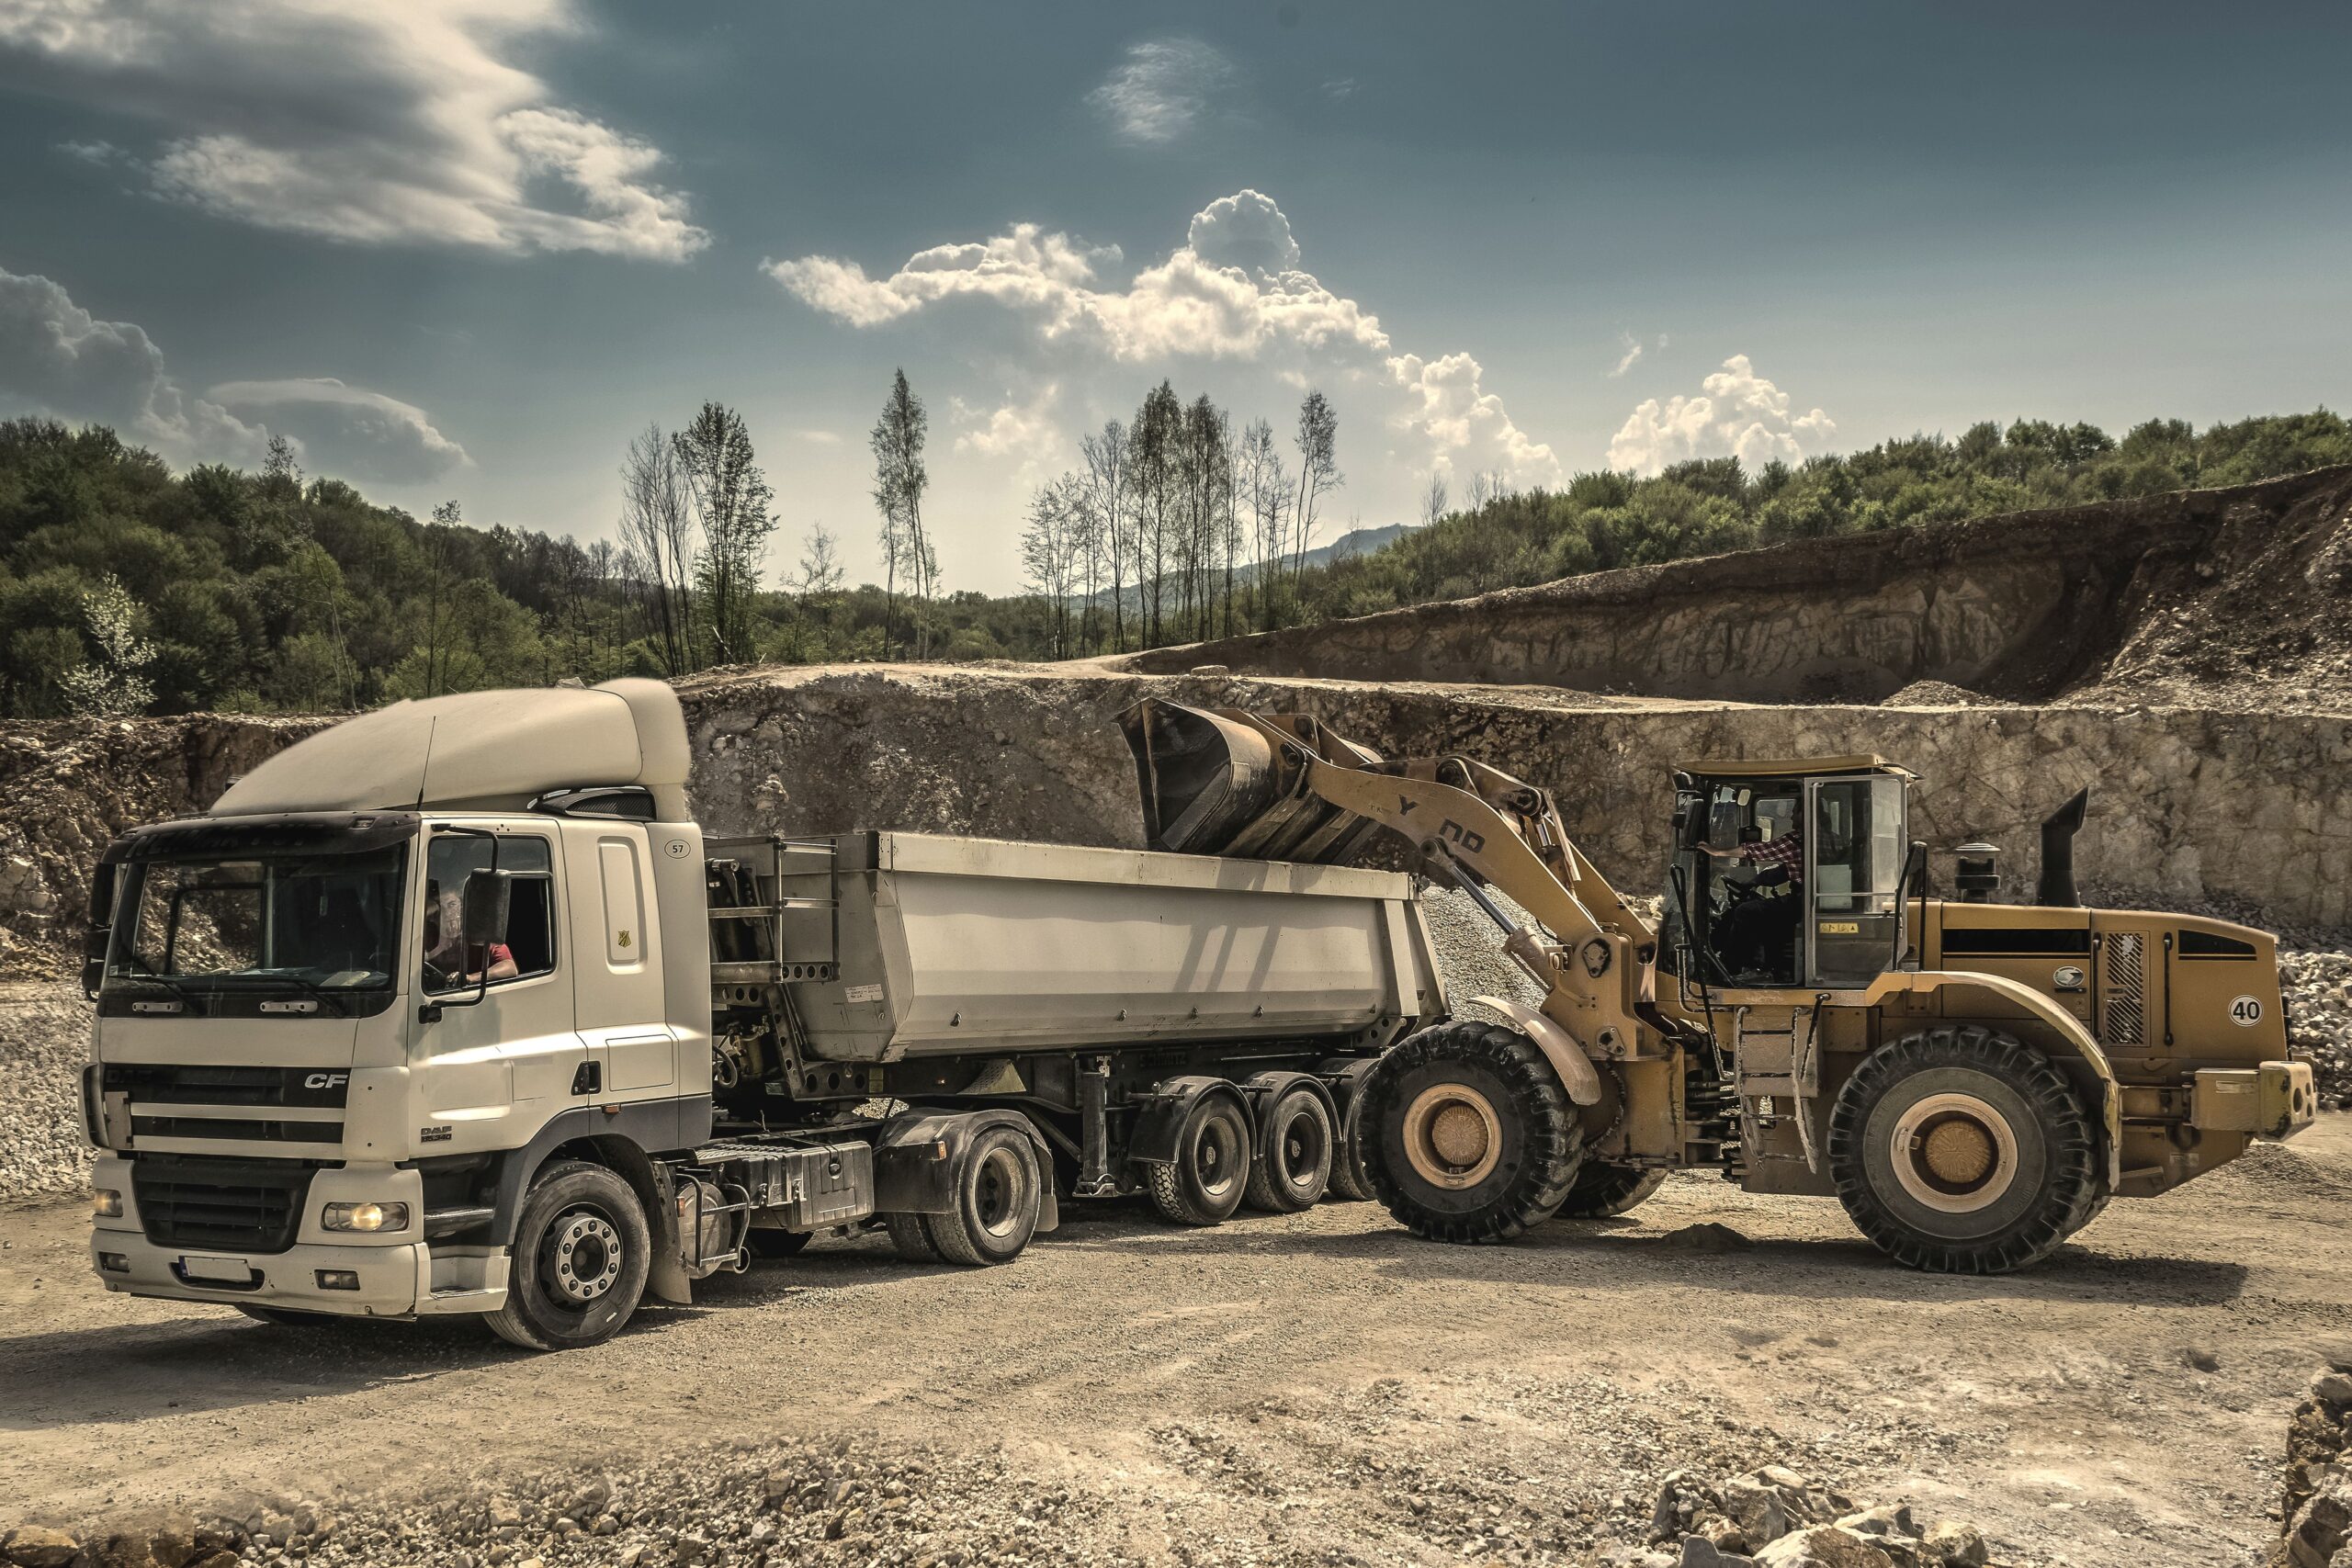
Uncertainties remain regarding the pace of implementation. The “major bureaucratic hurdles” cited in recent analyses could delay the 2027 ramp-up of Tía María and other expansions. Furthermore, the physical risks posed by climate change, as evidenced by the storms affecting Chilean operations and the El Niño conditions in Peru, introduce an element of unpredictability that capital models may not fully account for. The distinction between official project timelines and actual operational readiness is a key area of divergence, with market participants watching closely for any signs of regulatory gridlock.
For the Peruvian economy, the outcome of these projects will have far-reaching implications beyond the mining sector itself. The US$8 billion in new investment will stimulate local supply chains, logistics networks, and service industries. However, the benefits are contingent on the successful resolution of community and regulatory conflicts surrounding projects like Tía María. The sector’s ability to deliver on its 2027 targets will be a test of Peru’s capacity to balance resource extraction with sustainable governance and social license to operate.
As the industry looks toward 2027, the focus remains on the specific milestones for Tía María and the broader Southern Copper pipeline. The next critical data points will be the official permitting decisions and the physical progress of the infrastructure works. If these hurdles are cleared, Peru’s 12% share of global reserves could translate into a proportionally larger share of global supply, reinforcing its status as a cornerstone of the international copper market. The coming months will reveal whether bureaucratic efficiency can keep pace with the accelerating global demand for critical minerals.