
The move away from tech was visible in the sharp declines of non-Dow constituents like Oracle, Marvell, and Lumentum, which dropped between 6% and 18% on the day. Within the Dow itself, the impact was more muted but notable: Nvidia slipped approximately 0.5%, and Apple declined 2% ahead of its earnings release. Conversely, industrial and retail giants attracted buying interest. Sherwin-Williams gained 5.6% and Home Depot added 3.3%, bucking a backdrop of the sharpest monthly fall in construction spending since April 2020, driven largely by the housing sector. This divergence suggests investors are seeking exposure to companies with immediate pricing power and tangible earnings, rather than speculative long-term AI growth stories.
Macro data supports this pivot toward industrials. The Institute for Supply Management (ISM) factory index came in at 55.5, exceeding the forecast of 54.6, indicating continued expansion in production. Critically, the ISM prices index eased to 75.2, signaling a moderation in cost pressures. Combined with a fall of more than 7% in crude oil prices following President Trump’s statement that he was in no rush to resume hostilities with Iran, manufacturing firms are facing a more favorable cost environment. Dow manufacturers such as Honeywell, 3M, and Boeing capitalized on these conditions, each gaining more than 2% as lower fuel costs and expanding orders boosted sentiment.
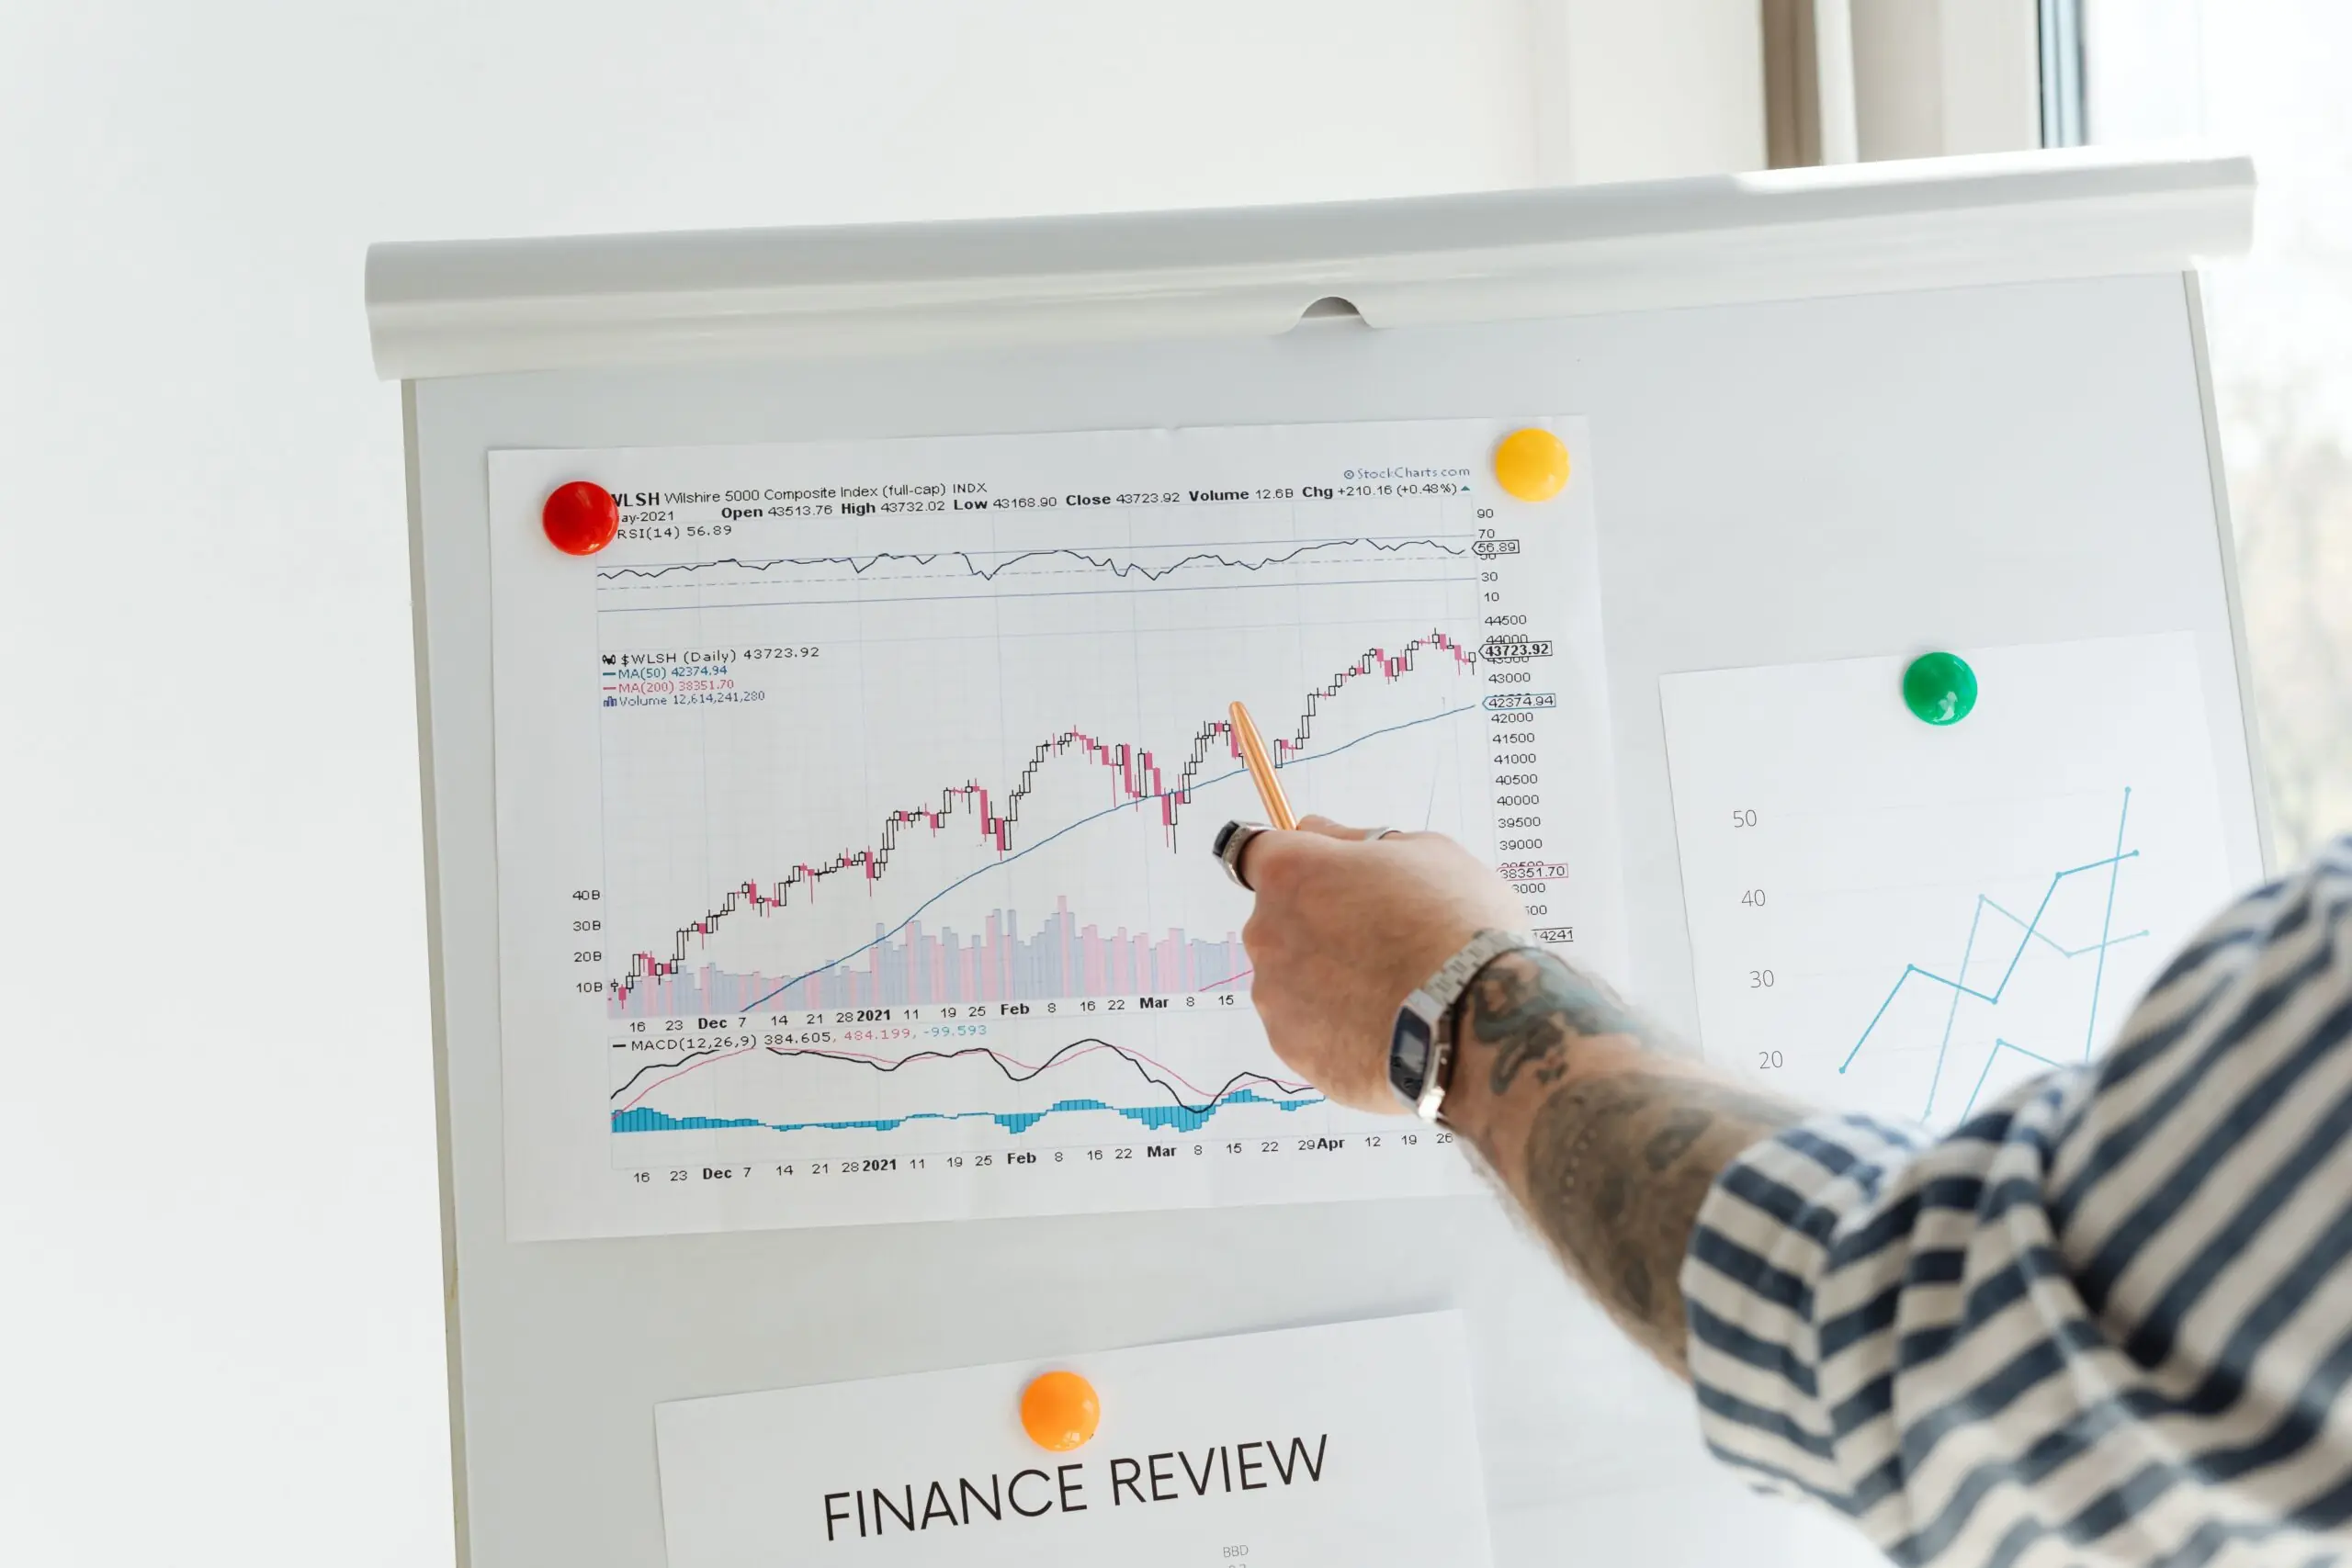
However, the path forward is not without technical and macroeconomic hurdles. The Dow has retraced more than a third of its advance from the October 1 low of just above 50,500 to its late-October high near 52,900. Currently, the index sits slightly below its 50-day Exponential Moving Average (EMA) of approximately 52,100, though it remains comfortably above the 200-day EMA near 50,750. After two weeks in overbought territory, daily momentum has cooled, suggesting a period of consolidation rather than a breakaway rally. The index’s price-weighted structure, which divides the sum of constituent prices by a factor currently standing at 0.152, means that high-priced stocks carry greater influence, a structural quirk that critics have long argued limits its representativeness compared to the S&P 500.
Analysts point to fundamental strengths beyond the AI cycle. S&P Global Market Intelligence, citing Visible Alpha analyst consensus estimates, identified an approximately 18.7% weighted potential price return for the 30 Dow companies over a medium-term horizon. This estimate is driven by strong earnings expectations in industrial and energy sectors, with companies like Caterpillar and Chevron benefiting from improved outlooks. Healthcare firms, including Johnson & Johnson, Amgen, and Merck, have also contributed to the index’s resilience. The research highlights that if industrial companies can maintain pricing power while production volumes increase, their earnings could support a broader market recovery, offering diversification away from the volatile tech sector.
Nevertheless, the Federal Reserve’s policy stance remains a critical variable. The federal funds target range stands at 3.75%–4.00% following the October meeting. While declining oil prices may eventually ease inflationary pressures, strong manufacturing activity and resilient economic growth could reduce the urgency for rate cuts. Higher borrowing costs continue to affect the Dow through multiple channels: industrial companies face expensive financing for equipment and investment, while consumer companies risk weaker demand as households manage higher debt service costs. Investors will closely watch the November 6 employment report for signals on job creation and wage inflation, with forecasts predicting 65,000 new jobs compared to the previous 29,000, and an unemployment rate expected to remain at 4.2%.
Market outlooks vary based on geopolitical and economic conditions. A base scenario suggests the Dow consolidates within the 51,500–54,000 range through year-end, supported by healthcare, industrials, and financials, assuming oil prices stabilize and earnings remain resilient. A bullish scenario hinges on meaningful progress toward a US-Iran agreement and further declines in energy costs, which could drive broader market breadth. Conversely, bearish risks include renewed selling post-midterm elections, weaker corporate earnings, or a resurgence in oil prices toward $120–$130, which could strengthen inflation expectations and force the Dow to test the 49,000–50,000 area. The next key data releases, including September job openings and the ISM services index, will be crucial in determining whether the rotation into value and industrials is a sustainable trend or a temporary tactical adjustment.