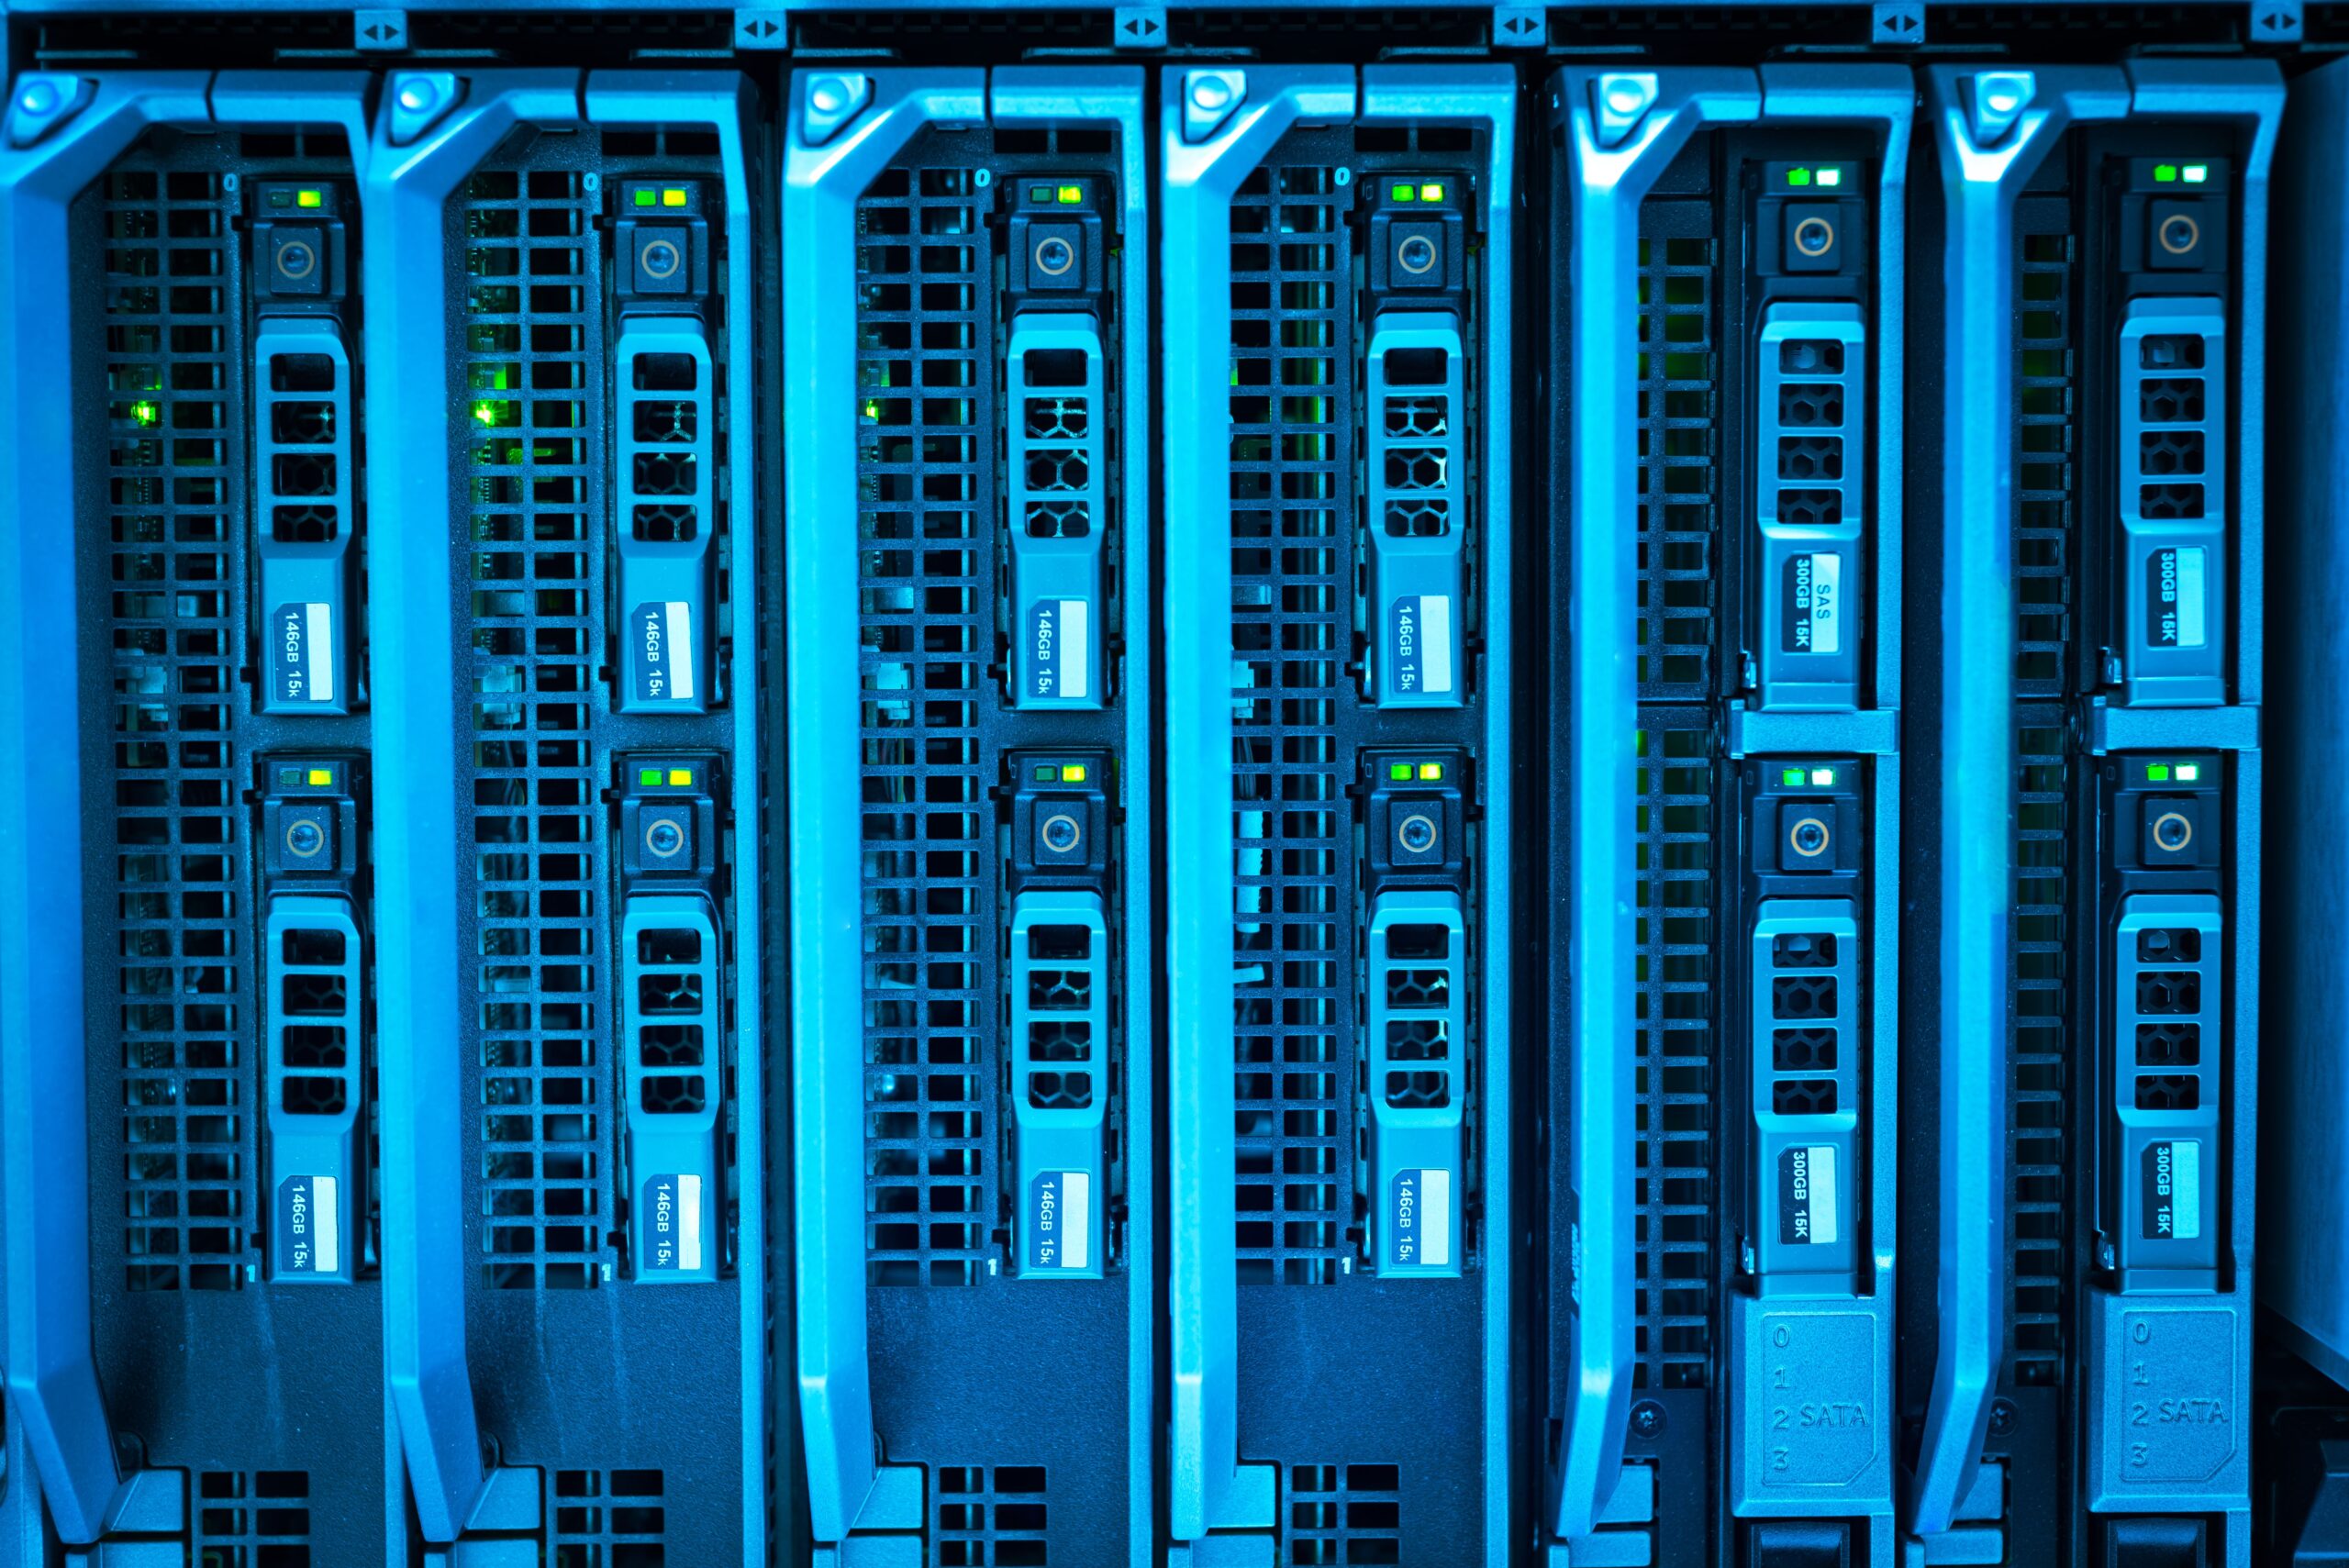
At its core, Super Micro Computer is a major provider of high-performance computing solutions, particularly AI servers that power large language models and data-intensive workloads. The technological significance of its recent market movement lies in what it reveals about investor confidence in the AI infrastructure boom. As hyperscalers and enterprise entities continue to invest heavily in GPU-dense racks and liquid-cooled systems, SMCI remains a key vendor in this supply chain. The analyst note suggests that the “wider technology story” is one of overreaction. When the market “goes too far,” it implies that the price adjustment has exceeded what can be justified by verified changes in revenue, margins, or competitive positioning. The report’s upgrade to “Strong Buy” is a direct counter-narrative to the prevailing bearish sentiment, positing that the company’s ability to deliver customized, rapid-deployment server systems remains a durable competitive advantage.
Understanding the mechanics of this valuation gap requires looking at how AI hardware stocks are perceived versus how they operate. Unlike consumer-facing software, where user adoption metrics provide immediate feedback, hardware vendors like SMCI are judged on order backlog, shipment volumes, and supply chain efficiency. The “evidence” supporting the analyst’s claim of excessive selling is not a new benchmark or a customer testimonial, but rather the discrepancy between the stock’s recent decline and the company’s ongoing role in the AI buildout. The report does not cite a specific new technical failure, a failed audit, or a loss of a major contract as the trigger for the drop. Instead, it frames the decline as a market sentiment issue. This distinction is crucial: it separates observed financial behavior (the stock price drop) from fundamental technical reality (the company’s operational status).
Who is affected by this narrative? Primarily, it is the institutional and retail investors holding SMCI equity. For developers and enterprises using Super Micro’s hardware, the immediate operational impact is negligible; the servers in their data centers continue to function based on their specifications, not the stock price. However, the financial volatility can impact the company’s ability to raise capital for R&D or expand manufacturing facilities. The “technical limitations” mentioned in the context of the AI sector generally refer to the physical constraints of power and cooling, which SMCI addresses through its liquid-cooling innovations. The analyst note implies that these technical strengths have not changed, yet the market has priced in a level of risk that the report deems unwarranted.
The commercial context here is defined by the race for AI infrastructure. Super Micro competes with Dell, HPE, and Lenovo in the server market, but its agility in offering customizable, rapid-turnaround systems has been a key differentiator. The “Strong Buy” rating suggests that the analyst believes the current market price underestimates this capability. There are no new privacy, security, or regulatory questions raised in the source material; the focus is strictly on equity valuation and market psychology. The report does not discuss data privacy concerns associated with AI training, nor does it detail any cybersecurity incidents. The narrative is confined to the financial interpretation of the company’s market position.
It is important to distinguish between the analyst’s opinion and verified fact. The source material provides the title and the core argument of the report: that the market has overreacted and the stock is a strong buy. It does not provide the detailed financial models, specific earnings numbers, or comparative data that underpin this conclusion. Therefore, while the claim of “excessive” selling is presented as the report’s finding, the user should treat this as an expert interpretation rather than an objective measurement of the company’s health. The “observed behavior” is the stock’s volatility; the “company claim” or analyst assertion is that this volatility is misplaced.
The social and institutional impact of such market swings is felt in the broader tech ecosystem. When a major hardware provider’s stock experiences significant distress, it can ripple through the supply chain, affecting suppliers of GPUs, memory, and cooling components. However, the source material does not detail these secondary effects. The primary impact is on the perception of the AI sector’s maturity. If the market continues to punish hardware vendors based on sentiment rather than delivery, it may distort investment flows away from the physical infrastructure required for the next generation of AI models. The analyst’s intervention serves to correct this perception, arguing that the fundamental story of AI hardware demand remains robust.
Returning to the initial moment of market tension, the “Strong Buy” upgrade acts as a stabilizing signal. It suggests that the next confirmed development for Super Micro Computer will not be a technical pivot or a strategic retreat, but a potential re-rating of its equity based on its continued execution in the AI server market. The unresolved technical issue is not one of engineering, but of valuation. As the market digests the analyst’s argument, the focus will remain on whether the company’s financial performance matches the optimistic outlook, or if the “excessive” selling was, in fact, a justified correction to overhyped expectations. The narrative remains open, hinging on the next set of verified financial results that will either vindicate the market’s caution or confirm the analyst’s conviction.