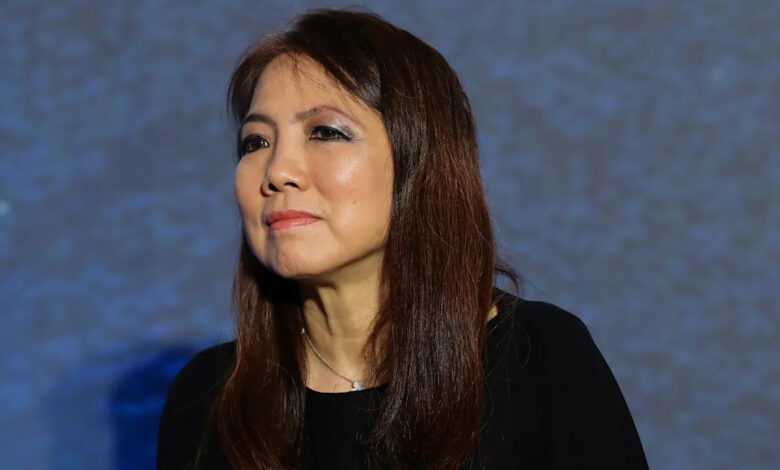
Speaking on the sidelines of a conference in Singapore, Tan indicated that the current environment is forcing a more rigorous examination of risk. “It’s not a bad thing because now, people are asking for higher returns, and people are also looking at structures,” she said. The core change is in the level of scrutiny applied to the capital being injected into the sector. Investors are no longer simply providing liquidity; they are ensuring that the massive amounts of money flowing into the AI capital expenditure ecosystem will generate a long-term return on investment sufficient to repay debt, bond, and equity holders.
Structuring Sustainable Debt
This repricing of risk is particularly significant given the scale of the commitments involved. DBS has originated approximately S$25 billion (US$20 billion) in AI-related deals so far this year. In most of these transactions, the bank acts as the lead manager for syndicated loans, coordinating financing from multiple lenders while retaining only a fraction of the total exposure on its own balance sheet. The majority of this financing supports the physical hardware underpinning AI, including semiconductors, memory chips, and data centers.
The shift in market sentiment is driven by a confluence of rising interest rates and a demand for financial sustainability. As the cost of funding increases, the margin for error in AI projects narrows. Tan noted that while the repricing may result in credit rating downgrades for financially weaker firms, it serves a protective function for the broader system. By demanding higher returns and stricter structural safeguards, the market is attempting to ensure that large financial commitments remain sustainable over the long term, rather than relying on perpetual low-cost capital.
“They’re making sure that whatever money is now being hoovered into the whole AI capex ecosystem will lead to some kind of long-term ROI that can then be repaid back to debt or bond or equity holders.”
— Tan Su Shan, DBS Group CEO
The broader context for these financial adjustments is a global race to build AI infrastructure. Estimates suggest that cumulative spending on data centers across Asia-Pacific could reach US$8.2 trillion by 2050. Against this backdrop of trillions in projected capital expenditure, the current tightening of financial terms reflects a maturing market. Investors are whipsawed by swings in AI stocks and are increasingly wary of exposure to companies whose business models have not yet demonstrated the ability to service their heavy debt loads.
For institutions like DBS, the implications are two-fold. On one hand, the bank’s internal adoption of AI is beginning to yield tangible results, including fee growth and a faster pace of new account openings as workflows are overhauled. On the other hand, the bank’s role as a key financier for the sector requires it to navigate a landscape where risk is being priced in more aggressively. Tan highlighted that while short-term market swings affect fluid capital flows, the long-term structural tailwinds for wealth management and banking in Asia remain strong, driven by capital market deepening and intergenerational wealth transfer.
The current volatility in interest rates, which Tan described as exhausting, signals that the era of easy money for AI infrastructure is ending. As the market continues to assess which firms can sustain their AI ambitions, the focus has shifted from pure speculation to verified long-term viability. For the lenders and borrowers defining the next phase of the AI economy, the question is no longer just about access to capital, but about the structural integrity of the deals being made to support it.