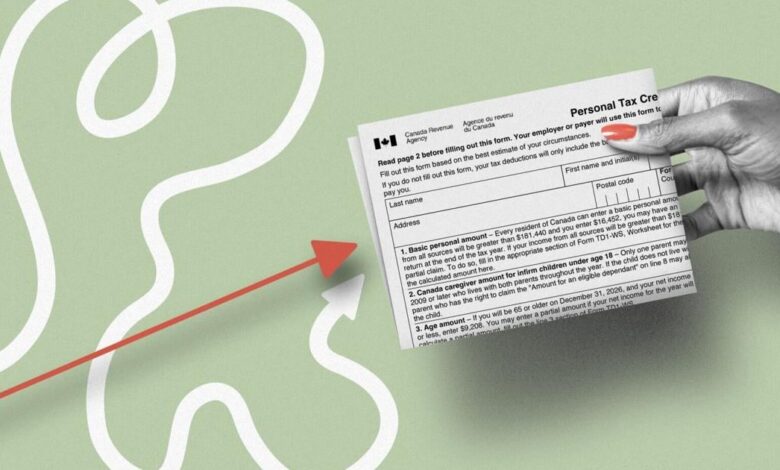
The central economic development in this fiscal package is a shift toward administrative efficiency and targeted corporate investment incentives. Jason Heath, a certified financial planner and managing director at Objective Financial Partners, notes that the budget does not propose significant tax reductions or new incentives for the general population. Instead, it focuses on administrative changes that make the tax system “a little bit easier going forward.” This approach reflects a broader governmental strategy to enhance cultural and economic sovereignty while addressing affordability through specific, rather than universal, mechanisms.
The impact on households is most visible in the adjustment of existing benefit structures. The budget proposes a one-time supplement to the Canada Groceries and Essentials Benefit (CGEB), equivalent to half of the maximum yearly amount, to be paid out in early 2027. For families, this supplement would amount to a maximum of $223 per adult and $117 per child, while singles would receive a maximum of $117. Additionally, the Canada Workers Benefit (CWB), a refundable tax credit designed to supplement the earnings of low- and modest-income workers, is being topped up and renamed the Build Canada Workers Benefit. Under the new structure, singles without children could receive a maximum annual payment of $1,859, an increase from the previous $1,709. For families, including couples and single parents, the maximum payment rises to $3,143, up from $2,943.
A notable structural change involves the Canada Caregiver Credit (CCC). Currently, the credit is non-refundable, meaning it only reduces the amount of tax owed. Consequently, caregivers with low incomes who already owe little to no tax receive no direct financial benefit. The budget proposes converting this into a refundable credit, allowing eligible caregivers to receive up to $1,260 annually even if they owe no taxes. Adam Pegler, a senior financial advisor, highlights that this change addresses a gap where individuals supporting family members “weren’t getting anything back” despite their caregiving roles.
While household measures focus on simplification and targeted support, the corporate sector faces more expansive policy shifts aimed at stimulating investment. The budget builds upon the Productivity Mega Deduction (PMD), announced in September 2025, which extended immediate expensing to nearly two-thirds of capital assets. This measure significantly reduced the after-tax cost of new business investment, a move described by the government as a “sea change in how Canada intends to stimulate business investment decisions.” It was also positioned as a response to similar measures adopted in the United States in July 2025.
Building on this momentum, Budget 2026 introduces the “Canada Growth Incentive,” designed to encourage investment in domestic companies. A key component of this incentive is a new $15 million capital gains exemption, along with enhanced rollover provisions for reinvestment in specific Canadian firms. The government is also broadening the Scientific Research and Experimental Development (SR&ED) tax incentive program and augmenting clean electricity and technology credits for corporations. Furthermore, enhancements to mineral exploration tax credits aim to expand resource development, signaling a continued commitment to the resource sector.
The budget also invites consultation on the sharing of corporate losses within corporate groups, introducing preliminary measures to address this area of tax law. These corporate-focused initiatives are intended to attract investment to Canada and support economic growth, aligning with the budget’s stated themes of affordability and strategic investment. KPMG and other financial institutions have noted that while the specifics of upcoming changes are often kept under wraps until release, this budget represents a clear pivot toward activist tax policy to drive business decisions.
Uncertainties remain regarding the long-term fiscal implications of these expanded credits and exemptions, particularly as the budget is still in draft form and subject to parliamentary approval. The interplay between the increased refundable credits for workers and caregivers and the substantial corporate tax incentives will determine the net effect on the federal deficit and public services. For now, the immediate effect is a reduction in the complexity of tax filing for over 1.5 million individuals and a clearer signal to businesses that the government is actively working to lower the cost of capital and investment.
As the legislative process moves forward, the focus will shift from the administrative simplifications to the implementation of the Canada Growth Incentive and the expanded SR&ED program. For the individual taxpayer, the changes mean a potentially later filing deadline and simpler forms, but for the broader economy, the budget marks a significant effort to use tax policy as a tool for industrial strategy and domestic investment.