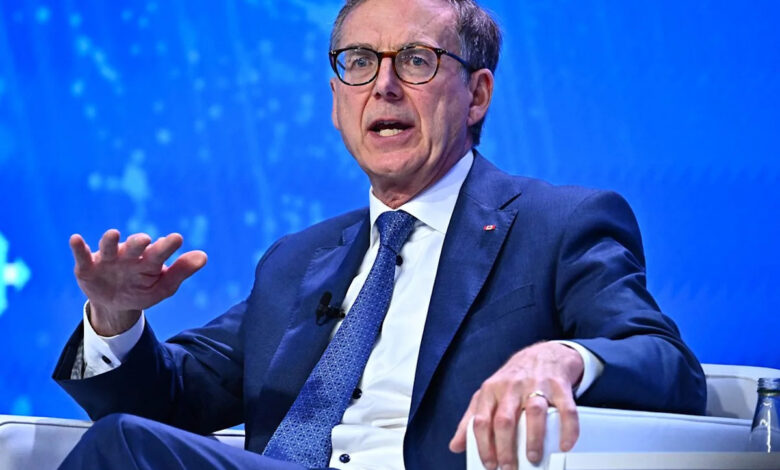
The Bank of Canada has held its overnight rate steady at 2.25 per cent for more than 11 months. Until recently, most economists predicted the central bank would remain on the sidelines, citing a lack of sufficient inflationary momentum to justify tightening. However, a sudden shift in tone from Bank officials, particularly Governor Tiff Macklem, has altered the analytical landscape. Macklem’s recent comments, made on the sidelines of International Monetary Fund meetings, signalled that the Bank’s economic outlook has changed materially since July. Officials indicated that they are finding it increasingly difficult to “look through” the direct impact of higher energy prices and are prepared to adjust the overnight rate to keep inflation expectations anchored.
Desjardins Group was among the first major institutions to revise its forecast, moving from a projected hold to an expectation of a quarter-point increase to 2.5 per cent. Randall Bartlett, Desjardins’ deputy chief economist, explained that new forward-looking data triggered this change. Specifically, roughly half of the firms surveyed in the central bank’s latest Business Outlook Survey reported plans to pass on some or all of their cost increases—stemming from the Iran war and tariffs—to consumers. Furthermore, firms that had previously absorbed some cost increases indicated intentions to continue passing them on.
“Both businesses and consumers increased their expectations for future inflation…. That led us to the conclusion that the Bank is going to be hiking rates on Wednesday of next week,” Bartlett stated. He noted that while businesses can absorb higher costs for a period, this capacity is limited. “The Bank of Canada certainly wants to get ahead of that by raising rates and tamping down on domestic demand, which has been strong in spite of all of these headwinds, and ultimately cooling off some parts of the economy to offset some of the heat that we’re seeing on inflation from other areas.”
RBC Economics has similarly revised its projections, now anticipating a hike to 2.5 per cent on Wednesday, rather than holding until the end of 2026. Nathan Janzen, assistant chief economist for RBC Economics, emphasized that while recent headline inflation data alone might not have been sufficient to compel a revision—given that core measures have remained relatively stable—the “hawkish” tone in official communications was the decisive factor. “The expectation next week is that they’ll raise it by a quarter (percentage) point, and that likely won’t be the last hike,” Janzen said. However, RBC cautioned that a hike is not guaranteed; the economy remains weak, with sufficient slack that could slow inflation passthrough. Janzen highlighted the delicate trade-off facing policymakers: “If they’re too slow to hike, they can let inflation pressures build unnecessarily, and if they’re too fast to hike, they can unnecessarily slow the pace of growth in the economy, and it looks like they’re leaning towards the former.”
Despite the consensus shift toward tightening, some economists argue the timing may be premature. Andrew Grantham, executive director and senior economist at CIBC Capital Markets, noted that the economy has not fully recovered from a sluggish 2025. Real gross domestic product (GDP) growth is expected to slow to an annualized rate of two per cent in the third quarter of 2026 and drop below one per cent in the fourth quarter. Nevertheless, CIBC’s forecasts now suggest the central bank may hike rates to 2.5 per cent in October and potentially to 2.75 per cent in December or January, aiming to bring the key interest rate to a neutral level where monetary policy is neither restrictive nor stimulative.
“(Macklem was) definitely hawkish relative to what economists and financial markets were forecasting prior to those comments,” Grantham observed. “Most people had assumed, given the uncertainty over trade and the impact that would have over the fourth quarter, along with the fact that core inflation measures haven’t picked up, that the Bank of Canada would need to raise interest rates in December or January.” He added that the growth outlook appears to be secondary to inflation concerns in the current decision-making process: “It would surprise us if the governing council doesn’t raise rates, given those comments…. The growth outlook isn’t impacting their decision. They are much more worried about inflation at the moment rather than some of the the quarterly volatility in terms of GDP.”
The implications of this potential hike extend beyond the policy rate itself, influencing bond yields and broader market sentiment. The central bank’s mandate involves balancing price stability with economic growth, a challenge that has become more acute amid external shocks. While U.S. tariffs are expected to dampen Canadian economic growth for the rest of the year, the Bank appears focused on preventing a de-anchoring of inflation expectations. As the governing council prepares to announce its decision, the market remains poised for a pivotal moment that could define the monetary policy path for the remainder of 2026 and into 2027.