**The European Debate: Mandates vs. Market Reality**
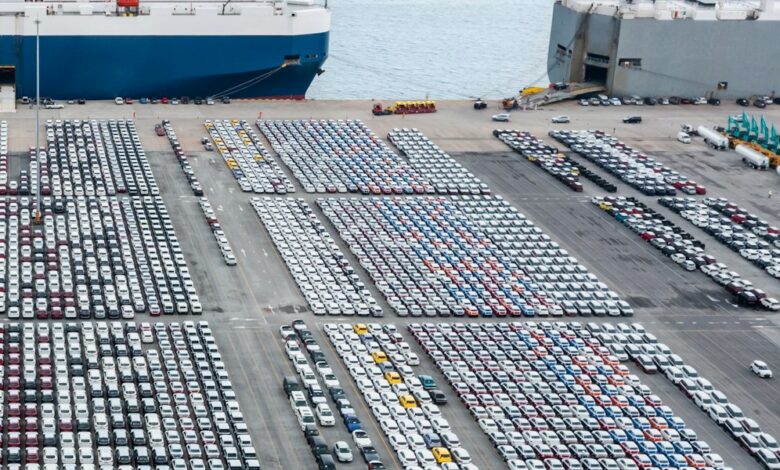
In Europe, the 2035 zero-emission mandate has become the focal point of intense industrial and political debate. Adopted by the European Parliament in 2022 to reduce CO2 emissions and costly fossil-fuel imports, the rule effectively bans the sale of new internal combustion engine (ICE) vehicles from 2035 onward. However, car manufacturers are now requesting revisions to allow plug-in hybrids (PHEVs) or vehicles running on biofuels. The industry argues that the current rule threatens the sector’s survival amid declining sales and factory shutdowns, compounded by intense competition from Chinese EV manufacturers.
Yet, the IEA’s analysis suggests this narrative may be misplaced. Data indicates that the European automobile sector’s crisis is structural and predates the EV transition. French vehicle production, for instance, has plummeted from 3.3 million units to 1.4 million units over 25 years. This decline is attributed less to the rise of EVs and more to a strategic failure to adapt to a shrinking market that increasingly favors premium, larger, and more expensive vehicles—a segment where German brands dominate. French manufacturers, historically specialized in smaller vehicles, lost EU market share from 25% to 15% between 2001 and 2023.
Crucially, EVs are holding up better than ICE vehicles in this shrinking market, particularly small French models. This challenges the industry’s justification for relaxing mandates. The IEA notes that France is well-positioned to produce more EVs, with significant investments already made in battery production and charging infrastructure. Relaxing the 2035 rule to allow ICE vehicles could therefore undermine a sector that is actually finding a foothold in the electric segment, while failing to address the core issue of strategic misalignment in vehicle design and pricing.
**U.S. Strategic Shifts and Policy Implications**
In the United States, the situation is marked by a different set of pressures. Recent reports indicate that U.S. automakers are pulling back from electric vehicles. This retreat is likely influenced by a combination of consumer price sensitivity, infrastructure gaps, and shifting political priorities. The *Global EV Outlook 2026* highlights that while the global EV market continues to grow, the pace and direction are being shaped by national policies and competitive dynamics.
For U.S. policymakers, the challenge is balancing the long-term benefits of electrification—such as improved air quality, lower driver costs, and energy security—with the short-term economic pain of transitioning an established manufacturing base. The IEA’s *World Energy Outlook 2025* and *Energy Technology Perspectives 2026* provide broader context, noting that the energy transition is not a linear process but a complex system-wide shift involving grid capacity, transmission constraints, and storage requirements.
**System-Wide Consequences and Investment Risks**
The divergence between European and U.S. strategies has significant implications for global energy markets and investment. For investors, regulatory uncertainty is a key risk. In Europe, the potential relaxation of the 2035 mandate could signal a shift in policy direction, affecting the valuation of EV supply chains, from battery plants to charging networks. Conversely, maintaining the mandate would signal a strong commitment to decarbonization, potentially attracting further investment in clean technologies.
The IEA emphasizes that the switch to EVs offers significant potential to improve air quality and lower costs for drivers over the vehicle’s lifetime. However, these benefits are contingent on a robust energy system. In the UK, for example, the transition is supported by industry efforts in automotive manufacturing and grid component building, enabling economic growth and thousands of jobs. The *Greenhouse gas emissions from transport in 2023* report by the Department for Transport highlights the role of EVs in reducing transport emissions, but also underscores the need for continued investment in charging infrastructure and grid upgrades.
**The Role of Charging Infrastructure and Grid Readiness**
A critical aspect of the EV transition is the readiness of the electricity grid. The IEA’s *Global EV Outlook 2026* stresses that EV adoption is not just an automotive issue but an energy system challenge. In the UK, ZapMap’s 2026 statistics show a growing network of EV chargers, but the IEA notes that grid connections and storage requirements must keep pace with the increasing number of EVs. The *Reducing non-domestic electricity prices to drive economic growth* report by Energy UK highlights the importance of stable electricity prices for industrial competitiveness, including the EV manufacturing sector.
In France, the investment in charging infrastructure is seen as a key enabler of the EV transition. The IEA notes that France’s position as a producer of small EVs aligns with the needs of urban and suburban drivers, who are more likely to adopt EVs. However, the success of this strategy depends on the availability of reliable and affordable charging options, both at home and in public spaces.
**Geopolitical and Competitive Dynamics**
The rise of Chinese EV manufacturers is a significant factor in the global landscape. The IEA’s *Global EV Outlook 2026* highlights that China is strong in the EV segment, posing a competitive threat to European and U.S. automakers. This competition is not just about price but also about technology, particularly in battery performance and charging speed. European manufacturers are responding by investing in their own battery production and EV platforms, but the IEA notes that the strategic focus on premium ICE vehicles has left them vulnerable in the mass market segment where EVs are gaining traction.
The geopolitical implications of the EV transition are also significant. The shift from oil to electricity reduces dependence on fossil fuel imports, enhancing energy security. However, the production of EVs and batteries requires critical minerals, such as lithium, cobalt, and nickel, many of which are concentrated in a few countries. The IEA’s *Critical Minerals* report highlights the need for diversified supply chains and increased recycling to mitigate supply risks.
**Conclusion and Outlook**
The *Global EV Outlook 2026* paints a picture of a global EV market in transition, with significant regional differences in strategy and policy. In Europe, the debate over the 2035 zero-emission mandate reflects a tension between long-term decarbonization goals and short-term economic pressures. The IEA’s analysis suggests that the sector’s crisis is more about strategic misalignment than EV adoption, and that maintaining the mandate could support a more competitive and sustainable European auto industry.
In the U.S., the pullback by automakers highlights the challenges of achieving a just and equitable transition, where the benefits of electrification are shared broadly. The IEA emphasizes the need for coordinated policies that address both the demand side (consumer incentives, charging infrastructure) and the supply side (manufacturing, workforce training).
The next critical milestone for the global EV market will be the implementation of national and regional policies in 2026. In Europe, the outcome of the debate over the 2035 mandate will be a key indicator of the sector’s direction. In the U.S., the response of automakers and policymakers to the current market conditions will shape the pace of the transition. The IEA’s *Global EV Outlook 2026* provides a data-led framework for understanding these developments and their implications for energy security, investment, and climate goals.
The upcoming *Oil Market Report* and *World Energy Outlook* will provide further insights into the interplay between fossil fuels and the energy transition. As the global economy moves toward a low-carbon future, the EV sector will remain a central pillar of the energy system, with its success dependent on integrated policies that address the complex challenges of technology, infrastructure, and market dynamics.